

Blogs
Driving Recorder Market Set for 8.5% CAGR Growth Through 2032: Strategic Shifts Redefining Profitability
By PW Consulting, 2026-09-21
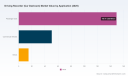
The Driving Recorder Market: Strategic Shifts and Commercial Opportunities from 2025 to 2032
The global market for driving recorders, commonly known as car dashcams, has grown from approximately US$163 million in 2020 to an estimated US$215 million in 2025. This trajectory reflects a compound annual growth rate of roughly 8.5 percent through 2032, when revenue is projected to exceed US$344 million. Behind these figures lies a sector undergoing structural transformation: what began as a consumer safety accessory is evolving into a data-rich, connectivity-enabled platform that intersects fleet management, insurance telematics, and advanced driver-assistance systems.
The market is no longer defined solely by onboard video capture. Multi-lens configurations, artificial intelligence–based event detection, and cloud-synchronized storage are reshaping product expectations across passenger cars, commercial fleets, and specialized applications. At the same time, supply chain friction, memory cost volatility, and shifting regulatory frameworks are introducing both constraints and differentiation opportunities. The following analysis maps the forces reshaping the driving recorder landscape and outlines where strategic value is likely to accrue over the next three to five years.
Market Snapshot and Core Challenges Facing the Industry
Revenue across the global driving recorder market reached US$215 million in 2025 and is projected to expand to US$344 million by 2032, supported by an 8.5 percent CAGR over the 2026–2032 period. The segment has demonstrated resilience through recent macroeconomic volatility, with year-over-year growth resuming after a brief contraction in 2022.
PW Consulting
Two structural challenges are defining the near-term operating environment. First, cost pressure from memory and semiconductor inputs is compressing margins for hardware-first players. Memory chip prices used in dashcams have risen 80 to 90 percent since late 2025, driven by surging AI data storage demand and allocation-only procurement practices among leading suppliers. Semiconductor lead times have been climbing for a full year and spiked dramatically in early 2026, with top-component lead times reaching 40 weeks. These dynamics create inventory planning complexity, lengthen time-to-market for new model iterations, and favor companies with stronger supplier relationships or differentiated bill-of-materials strategies.
Second, the market is navigating a maturity inflection in the consumer segment while simultaneously opening a higher-value pathway in commercial and connected-vehicle applications. Single-lens dashcams continue to anchor a substantial share of revenue, but multi-lens and AI-enabled configurations are expanding as fleet operators, insurers, and OEMs seek richer data sets. The strategic question is no longer whether to add connectivity or analytics, but how to do so without triggering a margin squeeze from raw-material inflation or exposing the product to cyber and data-privacy vulnerabilities that accompany cloud-based architectures.
A third, more geopolitical challenge is emerging around export controls and hardware provenance. Policy activity, including the April 2026 House Foreign Affairs Committee markup of national security-focused bills such as the Stop Stealing Our Chips Act, signals a more active regulatory posture around semiconductor and electronics supply chains. For manufacturers that rely on cross-border component sourcing or assemble in specialized hubs, this trend introduces planning uncertainty and may accelerate regional sourcing shifts or dual-supplier strategies.
Key Drivers Shaping the Driving Recorder Market
Technological Innovation and the Shift Toward AI-Enabled Recording
The most consequential technological shift is the migration from passive recording to intelligent event detection and post-incident analytics. Recent product introductions illustrate this direction. In April 2026, Thinkware introduced its flagship U3000 dash cam with 4K/2K resolution, built-in front and rear RADAR sensors, Sony STARVIS 2 image sensors, ADAS alerts, and mobile-app connectivity. In March 2026, BlackVue released the DR770X Box triple-camera cloud-compatible system with a separate secure recording unit designed for enhanced parking surveillance in fleet applications. These launches reflect a broader industry move toward higher resolution, sensor fusion, and dedicated storage architectures that preserve evidence even when primary systems are offline.
The practical implication for manufacturers and fleet operators is that video is increasingly treated as one input within a larger safety and compliance data stack. AI-based event classification, driver behavior scoring, and voice alerts are reducing reliance on manual footage review. Geotab’s September 2025 launch of the GO Focus Plus AI dashcam, which incorporates voice alerts and a video intelligence platform reported to reduce risky driving behaviors by up to 95 percent in fleet pilots, is an early indicator of how analytics can translate directly into measurable safety outcomes. For companies evaluating product roadmaps, the opportunity lies in pairing reliable image capture with differentiated analytics, low-latency alerts, and integration-friendly data outputs.
Policy and Regulatory Dynamics Supporting Adoption
Regulatory and compliance trajectories are creating tailwinds for higher-quality recording solutions, particularly in commercial and fleet environments. Although the specific content and timing of regulations vary by jurisdiction, the broader direction favors evidence-grade documentation, driver safety accountability, and telematics integration. At the same time, policy activity around semiconductors and electronics adds a layer of operational complexity. The April 2026 markup of export-control-related bills and ongoing scrutiny of chip supply chains suggest that companies should treat supply chain resilience and component traceability as strategic priorities rather than back-office concerns.
The commercial opportunity here is twofold. First, fleet operators and insurance-linked programs increasingly prefer dashcam solutions that can demonstrate consistent functionality, clean data handling, and integration with existing compliance workflows. Second, OEMs and tier-one suppliers are exploring ways to embed recording capabilities more tightly into vehicle architectures. In February 2025, Magna International advanced next-generation front camera systems for OEMs that integrate higher-resolution imaging with onboard video recording capabilities within a single ADAS module. This type of integration suggests a future in which aftermarket and OEM recording functions converge, expanding the addressable opportunity while also raising the competitive bar for standalone hardware.
Demand-Side Evolution Across Passenger Cars and Commercial Fleets
Consumer demand continues to be driven by safety concerns, insurance incentives, and a growing expectation that vehicles should document incidents clearly and reliably. Passenger cars remain the largest application category, reflecting broad adoption of dashcams as both a protection tool and a driver-assistance aid. However, the most dynamic growth is occurring where recording intersects with operational value: fleet safety programs, driver coaching, claim verification, and parking-mode protection.
Commercial vehicles represent a smaller but strategically important segment. Fleet operators are drawn to multi-channel systems and cloud-compatible architectures that support centralized monitoring, evidence preservation, and integration with broader telematics platforms. The appeal of separate secure recording units for parking surveillance, as seen in recent BlackVue fleet-oriented offerings, underscores a practical need: commercial users want continuity of protection when vehicles are unattended, plus administrative simplicity when incidents occur. As parking-mode features and ADAS alerts become standard expectations in premium segments, products that fail to offer robust post-event capture or seamless mobile connectivity risk losing share in higher-margin applications.
Supply Chain and Cost Structure Pressures
The cost environment is a defining constraint for the sector. The sharp rise in memory chip prices and extended semiconductor lead times mean that hardware planners must balance performance upgrades against input-cost volatility. Suppliers and integrators that can secure allocation, diversify sources, or design around memory-intensive architectures will have an advantage in maintaining price competitiveness. At the same time, the trend reinforces the case for software and service margins, subscription-linked features, and analytics offerings that can generate recurring revenue independent of component cost cycles.
This dynamic also favors consolidation and partnership. Companies with established supplier relationships, regional manufacturing flexibility, or strong logistics capabilities are better positioned to manage lead-time volatility. Conversely, smaller hardware-only entrants may find it increasingly difficult to compete on both speed-to-market and cost discipline without a clear software, integration, or brand differentiation.
Competitive Landscape and Leading Strategies
The driving recorder market remains moderately fragmented, with five companies accounting for roughly 48 percent of revenue and three firms representing about 32 percent. This concentration suggests that leading players have meaningful brand and distribution advantages, yet the sector still leaves room for specialized entrants that address fleet, premium consumer, or OEM-adjacent use cases.
Dashboard Camera Market
Viofo, based in Shenzhen, has built a reputation around professional-grade dash cameras featuring Sony STARVIS 2 IMX sensors, 4K ultra-high-definition recording, and advanced multi-channel recording. Its positioning reflects a clear focus on image quality and multi-channel capture, which appeals to users who prioritize evidence-grade footage. BlackVue, headquartered in Seongnam-si, South Korea, competes in the premium segment with 4K UHD dash cams, cloud features, parking mode protection, and triple-camera cloud-compatible systems. BlackVue’s strategy leans toward connectivity and continuous protection, particularly in scenarios where vehicles are parked and unattended.
70mai, based in Shanghai, has positioned itself as an innovator in smart car electronics with intelligent dash cams that combine AI features, 4K recording, and safety enhancements. Its approach emphasizes intelligent functionality and broader vehicle-electronics integration, aligning with consumer expectations for connected devices. In North America, Garmin contributes an automotive portfolio that includes wireless backup cameras, voice-controlled models, and GPS integration, giving it an advantage in ecosystems where navigation and vehicle electronics are purchased together. Thinkware, based in Coquitlam, British Columbia, is recognized as a global leader in premium dash cams with 4K UHD, AI parking surveillance, ADAS alerts, and mobile-app connectivity. Thinkware’s advantage lies in bundling high-resolution recording with radar-based sensing and app-level interaction, which supports both consumer and fleet-oriented positioning.
Vantrue operates in the United States with a premium high-end lineup focused on 4K ultra-HD recording and multi-channel options for automobile security, reinforcing a niche for users who want comprehensive coverage in a single device. Nextbase, based in the United Kingdom, has built an award-winning portfolio around high-resolution recording, fleet-optimized solutions, and proven safety features, giving it a strong narrative in markets where fleet safety and image quality are deciding factors. Pittasoft, also headquartered in Seongnam-si, South Korea, is associated with BlackVue premium dash cams and emphasized capabilities in cloud security, parking surveillance, and advanced video analytics, underscoring how software and data-management value can complement hardware.
Recent developments suggest the competitive edge is shifting toward integration and analytics. Geotab’s September 2025 launch of the GO Focus Plus AI dashcam with voice alerts and a video intelligence platform, which reportedly cut risky driving behaviors by up to 95 percent in fleet pilots, highlights how behavior-reduction messaging and video analytics can become differentiating value propositions in fleet environments. Thinkware’s April 2026 U3000 launch and BlackVue’s March 2026 DR770X Box release reinforce a premiumization trend in which multi-camera setups, secure storage units, and sensor-enhanced ADAS alerts are becoming standard features in higher-tier products. Magna’s February 2025 work on OEM-integrated front camera systems with onboard video recording indicates that the boundary between aftermarket and factory-installed recording is beginning to blur, a development that could reshape channel dynamics over time.
The strategic takeaway is that winning products are increasingly defined by more than resolution or channel count. Differentiation is coming from cloud compatibility, parking-mode resilience, ADAS-linked alerts, behavior analytics, and integration with fleet or telematics platforms. Companies that can combine reliable capture with actionable data outputs and robust supply-chain execution are best positioned to defend margins and capture share in the next phase of growth.
Forward-Looking Trends and Commercial Implications
Trend 1: AI and Video Intelligence Become Baseline Expectations
Over the next three to five years, AI-based detection and video intelligence are likely to move from premium differentiators to baseline expectations, especially in commercial and fleet applications. Voice alerts, event classification, and behavior scoring will increasingly be expected alongside high-resolution capture. This shift creates opportunities for products that can translate video into measurable safety improvements and for service models that help operators act on footage without large manual review teams. It also raises the importance of algorithm reliability, false-positive management, and data governance, since poorly tuned analytics can erode trust quickly.
Trend 2: Convergence of Aftermarket and OEM-Embedded Recording
The integration of recording capabilities into ADAS-related modules, as signaled by Magna’s next-generation front camera systems, points toward a future where onboard recording is more tightly embedded in vehicle architecture. This convergence could expand adoption through factory channels while increasing competition for standalone aftermarket devices. Manufacturers that can offer complementary aftermarket products, retrofit solutions, or strong integration interfaces may be able to serve customers who choose either path. The risk is that purely hardware-focused aftermarket products lose relevance if OEMs make recording a standard part of the vehicle package.
Worldwide Car Video Monitors Market
Trend 3: Supply-Chain Resilience and Component Cost Management as Strategic Capabilities
With memory chip prices up significantly since late 2025 and semiconductor lead times extending toward 40 weeks for key components, supply-chain management is becoming a strategic capability rather than a procurement exercise. Companies that diversify memory sourcing, optimize storage architectures, and build allocation resilience will be better able to sustain product launches and pricing. There is also an opportunity to shift some value toward software, cloud analytics, and subscription-linked features that are less exposed to component cost swings. The primary risk is that cost pressure forces broad price increases before consumers or fleet buyers are ready to absorb them, potentially slowing volume growth in price-sensitive segments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize sensor quality, multi-channel reliability, and ADAS-linked alert features as core product pillars, since these are becoming table stakes in premium consumer and fleet segments.
- Invest in analytics, cloud compatibility, and parking-mode resilience that deliver measurable operational value, rather than competing only on resolution or channel count.
- Strengthen memory and semiconductor sourcing strategies now, including supplier diversification and storage-architecture optimization, to reduce exposure to lead-time spikes and component-price inflation.
- Prepare for OEM adjacency by designing products that can complement factory-installed recording or serve retrofit and aftermarket niches with clear differentiation.
For Investors and Capital Allocators
- Look for companies that have credible analytics roadmaps, cloud integration capabilities, and evidence of fleet or insurance-linked demand, since these areas are where margin expansion and recurring revenue are most plausible.
- Evaluate supply-chain resilience as part of the investment thesis, especially for hardware-heavy models that may face margin volatility from memory and semiconductor costs.
- Monitor convergence signals between aftermarket and OEM-embedded recording, as these can reshape channel economics, competitive moats, and long-term growth trajectories.
For Fleet Operators, Procurement Teams, and Insurance-Aligned Buyers
- Prioritize solutions that combine high-quality capture with cloud-synchronized storage, parking-mode protection, and ADAS alerts, since these features reduce risk exposure and simplify incident response.
- Evaluate integration with existing telematics or safety platforms before procurement, because the operational value of a dashcam often depends on how easily footage and analytics can be used in daily workflows.
- Consider total cost of ownership in the context of memory and hardware cost trends, and weigh products that offer differentiated analytics or behavior-reduction features against straightforward recording-only options.
The driving recorder market is moving beyond simple onboard video capture into a space where image quality, AI analytics, cloud connectivity, and supply-chain discipline jointly determine competitive outcomes. For companies and investors seeking to navigate this shift with confidence, detailed segmentation data, company-level revenue estimates, and region-specific demand dynamics can sharpen planning considerably. PW Consulting maintains a dedicated research practice covering this sector, and the full Driving Recorder market report provides deeper breakdowns and customized scenarios for manufacturers, investors, and procurement teams evaluating entry, expansion, or sourcing decisions.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Digital Employee Scheduling Improves Workforce EfficiencyHow Digital Employee Scheduling Improves Workforce Efficiency
By toolkitx, 2026-09-21
How Digital Employee Scheduling Improves Workforce Efficiency
Managing a workforce manually can quickly become far more complicated than it first appears. What begins as a basic employee roster can soon involve spreadsheets, phone calls, staffing gaps, shift changes, and constant questions about working hours. Even a small modification may result in several different schedule versions, leaving employees unsure about which information is accurate. Employee scheduling software addresses these difficulties by bringing workforce planning, staffing decisions, and schedule updates together within one centralized platform. Solutions such as ToolKitX go a step further by automating roster preparation and delivering schedule changes directly to employees through mobile access, helping organizations remain coordinated when plans shift unexpectedly.
What Is Employee Scheduling Software?
Employee scheduling software is a cloud based workforce management solution designed to help organizations assign the right employees to the right shifts more efficiently. Rather than depending entirely on manual calculations and separate scheduling decisions, the software can consider factors including employee availability, qualifications, certifications, skills, staffing needs, and workforce compliance requirements.
After schedules are reviewed and approved, they can be distributed digitally through web and mobile platforms so employees can access the most recent information. Over time, the platform can become a central hub for workforce activities such as shift planning, leave applications, approvals, and employee communication. Bringing these activities together eliminates scattered messages and outdated schedule files, creating a process that is easier to oversee, more consistent, and more dependable.
Why Scheduling Problems Can Become Expensive
Workforce scheduling challenges can affect considerably more than administrative efficiency. When too many employees are scheduled, labor expenses can rise without producing a corresponding increase in business value. When too few people are available, organizations may experience slower service, greater employee pressure, operational interruptions, and possible safety related concerns.
Unclear schedule communication can also contribute to missed shifts, late attendance, and frequent last minute adjustments. Modern scheduling platforms help address these challenges by bringing staffing requirements, workforce policies, employee qualifications, and operational restrictions together in a single environment. Automation reduces repetitive scheduling work, while improved visibility helps managers recognize potential overtime and coverage problems before they become larger operational issues. This creates a more organized scheduling process, reduces conflicts, and strengthens coordination across the workforce.
Key Features That Create Operational Value
Modern employee scheduling software is designed to do much more than replace a traditional calendar. Its broader purpose is to make workforce planning easier, increase visibility across teams, and reduce the manual work required to manage employees and shifts.
Automated Schedule Creation and Reusable Patterns
Building every roster manually from scratch can consume significant time during every scheduling cycle. Automated scheduling solutions can create more suitable rosters by considering staffing requirements, workforce policies, and operating conditions. Repeated shift arrangements can also be saved as reusable templates, allowing managers to apply established patterns instead of rebuilding them each time. ToolKitX expands this functionality with an AI powered scheduling engine that allows organizations to create schedules within minutes.
Centralized Planning Across Multiple Locations
Businesses managing several facilities, projects, teams, or shifts need a complete picture of workforce coverage. A centralized scheduling platform gives managers the ability to coordinate employees across different locations and teams while keeping availability, assignments, and operational requirements visible through one system.
Immediate Schedule Communication
After a roster has been approved, it can be distributed immediately. Employees can receive updated assignments and schedule changes through their mobile devices, reducing the need for phone calls, emails, and repeated circulation of revised schedule documents.
Simplified Leave Requests and Shift Changes
Employees can submit leave requests and arrange shift exchanges directly through the scheduling system. Managers can then review requests, authorize changes, and maintain visibility over the entire process. Approved activities are automatically recorded, creating a useful history that supports accountability and future reference.
Overtime and Compliance Visibility
Scheduling platforms can monitor factors such as overtime thresholds, certification requirements, staffing coverage, and working hour restrictions. This provides organizations with greater insight into workforce costs while helping them maintain alignment with applicable workforce requirements.
Connected Operational Workflows
Scheduling can become considerably more valuable when it connects with other operational processes. Linking workforce schedules with work orders, task management, project activities, and room scheduling can give decision makers a more complete view of how people and operations interact. It also reduces dependence on multiple disconnected systems and minimizes the need to maintain the same information in different places.
Industries That Can Benefit Most
Employee scheduling software can support organizations across many sectors, but industries with complex staffing requirements or changing workforce demands can particularly benefit from structured digital scheduling.
Field Services and Construction
Construction and field projects often require employees who possess specific qualifications, certifications, or site permissions. Scheduling software can make it easier to coordinate these workers while giving teams greater flexibility when projects experience delays, requirements change, or unexpected circumstances arise.
Manufacturing and Offshore Operations
Organizations running continuous operations need appropriate personnel available at specific times. Scheduling software can support workforce coverage and operational planning while accounting for practical considerations such as accommodation arrangements, resource availability, and logistical limitations.
Hospitality, Retail, and Customer Service Environments
Customer demand can change significantly according to the time of day, day of the week, or season. Scheduling software allows organizations to adjust staffing according to changing demand, helping them manage labor expenses while maintaining appropriate service levels.
How Modern Workforce Scheduling Works
Organizations moving toward digital scheduling can establish a more organized and efficient process for managing their workforce.
- Managers access the scheduling platform, choose an appropriate shift pattern, and begin automated roster generation using employee availability, qualifications, and role requirements.
- Before the schedule is released, the system evaluates the proposed roster and identifies potential issues, including overtime exposure, certification conflicts, or insufficient workforce coverage.
- Employees access their schedules through web or mobile platforms, review their assignments, submit leave requests, or request exchanges with other employees.
- Once requested changes have been reviewed and approved, employees receive timely notifications, ensuring that everyone is working from the latest version rather than an outdated schedule.
Measurable Business Advantages
The value of employee scheduling software goes beyond eliminating repetitive administrative work.
- Greater productivity: Scheduling activities that previously required hours of manual effort can often be completed in a much shorter period.
- More efficient workforce utilization: A clearer view of employee availability and staffing requirements allows organizations to align workforce levels more closely with operational demand.
- Fewer attendance issues: Real time schedule notifications reduce confusion and make it easier for employees to remain informed about changes to their shifts and assignments.
- Better employee experience: Easier schedule access, quicker approvals, and greater consideration of employee availability can contribute to a more positive workforce experience.
Implementing Employee Scheduling Software Successfully
Organizations transitioning away from spreadsheet based scheduling can often improve adoption by introducing the software gradually. A practical approach is to begin with one department or team that follows a recurring schedule, such as a 2 2 3 rotation or another repeatable shift pattern. Before implementation begins, organizations should establish clear workforce policies, qualification criteria, and operational restrictions.
Employee availability details can then be added to the platform, allowing managers to use automated scheduling for an initial planning cycle. During this stage, organizations should monitor practical measurements such as the amount of time required to create schedules, overtime levels, the frequency of shift adjustments, and the time taken to publish completed rosters. Once the process is stable and teams are comfortable using the system, scheduling can gradually be extended to additional departments, teams, and locations. Connecting scheduling with tasks, work orders, and room planning can create further coordination opportunities while supporting more efficient workforce management over the long term.
Book a free demo @ https://toolkitx.com/campaign/employee scheduling/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Cold work permit (2025 guide)%3A definition%2C OSHA%2FHSE mapping and checklist
https://toolkitx.com/blogsdetails.aspx?title=Refinery tank farms management: the digital imperative for safety and profit
https://toolkitx.com/blogsdetails.aspx?title=What is a Confined Space Entry Permit A Simple Guide
Histidine Market Outlook 2026–2032: The Real Drivers Behind a 6.8% CAGR
By PW Consulting, 2026-09-21
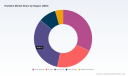
The Histidine Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global market for L-Histidine has entered a phase of steady, compounding expansion. From 2020 through 2032, the sector is projected to advance at a compound annual growth rate of 6.8 percent, with market value climbing from roughly $163 million to over $338 million over the forecast horizon. The trajectory is not a straight line: a contraction in 2022 underscored the fragility of supply chains, while post-pandemic recovery and downstream demand acceleration pushed the market past $215 million in 2025. This growth is anchored in biology as much as economics. Histidine’s role as an essential amino acid, a buffering agent, and a precursor in specialty formulations makes it indispensable across pharmaceuticals, animal nutrition, food processing, and life sciences research. Yet the market’s maturity is uneven, and the companies that will capture disproportionate value are those that understand where production is shifting, where regulation is tightening, and where end-use demand is evolving faster than capacity.
L-Alanine Market
Market Structure and Core Challenges
The histidine market is characterized by moderate fragmentation and a production base that leans heavily on two manufacturing paradigms. Fermentation-derived routes dominate the volume conversation, supported by steady gains in yield optimization and strain engineering. Hydrolysis-based production remains relevant where specific purity profiles or legacy supply arrangements dictate. The regional distribution of revenue reflects a geography in transition. Developed markets in North America and Europe continue to anchor high-value, regulated end markets, while Asia Pacific has emerged as both the largest consumption region and a critical production hub. Latin America and the Middle East and Africa contribute smaller but structurally important flows, often tied to feed-grade applications and emerging pharmaceutical manufacturing.
Against this backdrop, three structural challenges define the current operating environment.
PW Consulting Health Care Research Center
- Purity and regulatory divergence across applications. Pharmaceutical and biopharmaceutical demand requires GMP-grade, low-endotoxin, and low-metal specifications that are expensive to validate and qualify. Feed and food-grade applications operate on thinner margins and more price-sensitive procurement cycles. The gap between these tiers creates a bifurcated market where the same molecule carries radically different cost structures, qualification timelines, and competitive moats.
- Supply chain concentration and verification risk. A handful of large producers accounts for a modest share of total revenue, which means the market is not dominated by a single oligopoly, but it is also not broadly commoditized. Semi-concentrated supply, combined with geographic clustering of fermentation capacity, leaves downstream buyers exposed to qualification bottlenecks, logistics disruption, and batch-to-batch consistency concerns.
- Input volatility and the cost of biological production. Fermentation economics are influenced by substrate pricing, water and energy intensity, strain performance, and downstream purification costs. Hydrolysis routes face their own raw material dependencies. When energy prices or feedstock costs move sharply, margin discipline becomes a differentiator rather than a baseline expectation.
Key Drivers Reshaping the Market
The 6.8 percent growth rate is not merely an extrapolation of historical demand. It reflects a convergence of technical, regulatory, and commercial forces that are changing how histidine is produced, qualified, and deployed.
Technology and Process Innovation
Process innovation is the most direct lever for expanding margins and unlocking new use cases. In fermentation, the competitive frontier has shifted from basic titer improvements to integrated strain design, reduced impurity profiles, and more efficient downstream recovery. The practical impact is significant: higher-purity outputs lower the burden of endotoxin and metal removal, which in turn shortens qualification cycles for biopharmaceutical customers. For hydrolysis-based producers, the opportunity lies less in volume leadership and more in precise specification control where specialty grades command premium pricing.
This dynamic is visible in recent strategic moves to combine complementary capabilities. A notable example is the 2025 partnership between a major fermentation-based producer and a Chinese chemical supplier to co-develop and secure global supply of L-Histidine HCl monohydrate, explicitly aimed at expanding fermentation-derived production capacity. The significance of this move is not just incremental capacity. It signals a deliberate effort to align biological production expertise with regional supply reach, reducing lead-time risk and reinforcing supply continuity for regulated end markets. In an environment where qualification and consistency are as valuable as price, partnerships that bridge process technology and distribution are becoming a strategic necessity rather than an optional synergy.
Policy and Regulatory Environment
Regulation is quietly reshaping histidine’s cost of entry and the geography of trade. For pharmaceutical and biopharma buyers, GMP compliance, traceability, and impurity control are non-negotiable. For industrial and feed users, the regulatory burden differs, but documentation, residue limits, and regional approval pathways still shape sourcing decisions. The effect on competition is twofold: regulatory readiness functions as a barrier that rewards established, well-documented suppliers, while new entrants must invest not only in capacity but in quality systems and audit readiness.
On the trade side, export control dynamics add another layer of complexity. In early 2026, the U.S. Federal Register noted that China suspended export controls on six critical dual-use items until November 2026, with potential implications for trade in chemical intermediates used in amino acid production. Even where the direct link to histidine is indirect, the broader signal is important: the availability and pricing of intermediates, precursor chemicals, and specialty inputs can shift with regulatory calendars, not just market fundamentals. Producers and buyers that map their supply chains against such policy windows are better positioned to avoid surprise cost spikes or sourcing gaps.
Demand-Side Shifts
End-use demand is expanding along two converging paths. The first is the continued growth of biopharmaceutical manufacturing and cell-based processes, where histidine and its salts serve as excipients, buffering components, and media constituents. As biologics, cell therapies, and advanced manufacturing formats scale, the volume of high-purity amino acids required per facility increases, raising the stakes for suppliers that can deliver consistent, low-endotoxin material at commercial scale.
The second path is more traditional but structurally durable: animal feed and food-grade applications. In feed, histidine availability supports formulation flexibility and animal performance objectives, while in food and supplements it serves functional and nutritional roles. These segments are less glamorous than biopharma, but they contribute steady volume and can act as absorbers during periods when pharmaceutical demand is qualification-constrained. Importantly, the demand mix is not uniform across regions. Where animal production intensifies and where food processing modernizes, histidine consumption grows in ways that reward suppliers with reliable feed-grade and food-grade streams as well as the capability to serve regulated markets when opportunities arise.
Supply Chain and Cost Structure Evolution
The market’s cost structure is increasingly shaped by the distance between production and qualification. Fermentation scale brings advantages in unit cost, but it does not automatically solve purity, endotoxin control, or documentation. As a result, the most resilient supply chains are those that integrate fermentation output with disciplined downstream processing and strong quality systems. This integration reduces rework, shortens batch release timelines, and improves predictability for buyers who are themselves managing tight production schedules.
Logistics and geographic concentration also matter more than they appear to on a spreadsheet. A supply base that is efficient but geographically narrow can create hidden exposure: port delays, regional fuel cost fluctuations, and regulatory checks can each erode service levels. The practical response is diversification of qualified sources combined with audited quality agreements. Buyers are increasingly treating qualification as a portfolio decision, balancing cost against continuity, and favoring suppliers that can demonstrate both scale and verifiable control over critical quality attributes.
Competitive Landscape and Leading Strategies
The competitive set in histidine is geographically diverse and strategically differentiated. Japanese producers have built strong reputations in fermentation-based, high-purity supplies for pharmaceutical and biopharmaceutical use, with product profiles explicitly oriented toward cell culture media, parenteral and enteral nutrition, and biopharmaceutical applications. A leading German specialty supplier has emphasized highly purified histidine for biopharma, amino acid derivatives, and GMP-grade applications, reinforcing a positioning around purity and compliance. Another major European life sciences player has extended its brand into histidine for laboratory and biopharma use, leveraging established quality systems and broad distribution networks.
Lysine Market
In the United States, a supplier focused on high-purity, low-endotoxin, low-metal material has carved a defensible niche in biopharmaceutical formulations, where impurity control and specification consistency directly affect customer outcomes. In Asia, a Korean fermentation producer supplies histidine base for medicines, food supplements, and animal feed, reflecting a model that spans both regulated and lower-margin volume applications. China-based chemical suppliers remain active in pharmaceutical and industrial streams, often competing on responsiveness and cost while navigating the same quality expectations as global buyers.
Several patterns stand out in how leading players are positioning themselves.
- Segment specialization as a moat. The most defensible positions are not simply about volume. They are about owning a specification tier that matters to a specific customer class. High-purity, low-endotoxin material creates switching costs because re-qualification is expensive and time-consuming. Feed-grade and food-grade leadership, by contrast, requires scale, cost discipline, and reliable delivery. Few companies optimize both tiers equally, which is why specialization remains a rational strategy.
- Capacity expansion tied to partnership, not just CAPEX. The recent co-development partnership to expand fermentation-derived supply illustrates a broader trend: companies are extending reach through alliances that combine process know-how, regional access, and supply security. This reduces the capital intensity of standalone expansion while improving resilience.
- Quality systems as commercial infrastructure. In regulated segments, quality documentation, audit readiness, and impurity control are no longer back-office functions. They are commercial differentiators that determine whether a supplier is invited into a qualified vendor list in the first place.
The market structure suggests continued evolution rather than abrupt consolidation. Because concentration is moderate, the field remains open to capable new entrants with strong process or quality advantages, but the qualification barrier protects incumbents who have already invested in relationships and documentation. Over the next few years, the most likely shifts are selective integration around capability gaps—partnerships, co-development, and regional supply reinforcement—rather than broad-based mergers. At the same time, buyers are likely to keep qualifying multiple sources where possible, balancing cost and continuity, which will reinforce the value of differentiated quality and reliable service.
Future Trends and Commercial Implications
Looking ahead three to five years, three trends are likely to shape where value migrates within the histidine market.
First, the premium on high-purity, biopharma-ready material will keep rising. As biologics manufacturing and advanced cell-based processes scale, demand for low-endotoxin, low-metal, well-documented histidine will grow faster than the general market. The commercial opportunity lies in building or acquiring the process control and quality systems that make that purity reproducible at scale. Suppliers that can compress qualification timelines and reduce variability will be able to command pricing power even in an otherwise competitive category.
Second, production geography will keep rebalancing around cost, continuity, and policy. Asia remains a central production axis, but buyers are likely to seek qualified alternatives and redundancy where possible. Trade and export-control dynamics may also influence intermediate availability, which will make forward inventory planning and supplier mapping more important. Companies that treat geography as a risk variable—not just a cost variable—will be better prepared to maintain service during disruption.
Third, segmentation will sharpen rather than blur. The gap between regulated pharmaceutical grades and feed/food grades is structural, and the strategies that succeed in one segment do not automatically transfer to the other. That creates both risk and opportunity. Manufacturers that can selectively bridge high-margin, high-specification demand with stable volume streams will capture more resilient economics than those forced to compete purely on price in undifferentiated segments.
Each trend carries uncertainty. Regulatory expectations may tighten further in certain jurisdictions, raising the cost of entry for new suppliers. Energy and feedstock volatility can compress margins for fermentation producers that lack pricing power or hedging discipline. And while partnerships can extend reach, they also introduce coordination risk, especially when co-developing capacity across regions with different regulatory environments and operating norms. The most resilient strategies will account for these variables explicitly rather than assuming smooth demand growth will absorb operational shocks.
Actionable Guidance for Decision Makers
For manufacturers, the strategic question is where to invest next. If the portfolio already leans toward feed or food grades, the highest-return move may be disciplined expansion of purification capability that opens a credible path into pharmaceutical or biopharma-adjacent specifications. If the portfolio already serves regulated markets, the priority is likely to reinforce supply continuity through partnerships or regional capacity that reduces lead-time exposure, while maintaining rigorous impurity and endotoxin control. In both cases, qualification readiness should be treated as part of the product, not a separate compliance exercise.
For investors, the opportunity is less about total market size than about the distribution of value within it. Segments that require high purity, low variability, and documented compliance tend to support more durable margins and stronger customer stickiness. Capital should be assessed against the ability to scale process control, reduce batch failure and rework, and qualify sources in multiple geographies where appropriate. Projects that rely on undifferentiated volume growth without a quality or continuity advantage are more exposed to margin compression and competitive entry.
For procurement and supply chain leaders, the practical priority is to convert qualification from a one-time gate into an ongoing risk-management process. That means evaluating suppliers not only on price and lead time, but on impurity profiles, endotoxin and metal control, documentation depth, and the resilience of their production geography. Multi-sourcing qualified alternatives, even where one supplier dominates volume, can reduce exposure to disruption. Aligning inventory planning with potential policy windows and trade dynamics—such as the recent suspension of certain export controls affecting chemical intermediates—can also prevent avoidable cost shocks.
For organizations evaluating where to focus next, the histidine market rewards precision. The growth rate is healthy, but the real differentiation comes from understanding which specification tiers are expanding fastest, where supply is becoming more or less concentrated, and how regulatory and trade dynamics will alter the cost of intermediates and finished material. A detailed segmentation view—by production method, application tier, end-market requirements, and regional qualification pathways—can sharpen capacity planning, sourcing strategy, and investment prioritization in ways that aggregate market figures cannot. For teams that need segment-level sizing, region-specific supply analysis, and tailored scenarios for qualifying new sources or expanding into higher-purity grades, the full research report provides the structured data and actionable detail to support those decisions.
For detailed analysis of this topic, please visit the official page: Histidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vinylphosphonic Acid Market: Why 8.7% CAGR Through 2032 Changes Everything
By PW Consulting, 2026-09-21
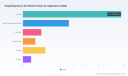
Vinylphosphonic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for vinylphosphonic acid (VPA) has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 10.8 million USD in 2020 to an estimated 16.4 million USD in 2025. The trajectory points toward continued growth, with the market projected to reach nearly 29.3 million USD by 2032, reflecting a compound annual growth rate of 8.7 percent. This scale places VPA in the niche specialty chemicals segment, where volume is modest but value addition through application-specific performance is substantial.
At first glance, the numbers suggest uninterrupted expansion. Closer examination reveals a market that is fragmenting around performance thresholds rather than pure capacity. The revenue distribution across grades, applications, and geographies shows that demand is not uniform. High-purity grades dominate share, while coatings and water treatment applications account for the bulk of consumption. Asia Pacific leads regional contribution, reflecting concentrated industrial activity and manufacturing capacity in the region, while mature markets in North America and Europe sustain steady, high-value demand.
PW Consulting
Despite the positive outlook, the sector faces structural challenges that complicate straightforward growth strategies.
Challenge One: Purity Thresholds and Application-Specific Performance
The market is no longer defined by generic chemical supply. Buyers in coatings, corrosion inhibition, and polymer modification increasingly require tight impurity profiles and consistent batch-to-batch performance. The shift from 80 percent grades toward 90 percent and higher purity thresholds is reshaping procurement logic. Suppliers that cannot demonstrate controlled impurity levels risk being relegated to lower-margin segments, while those that can command premium positioning and longer-term contracts.
Challenge Two: Feedstock Volatility and Cost Structure Pressure
Production economics are tightly coupled to phosphorus-based feedstock availability and pricing. Raw material price volatility affects a significant portion of global producers, placing pressure on margin forecasting and inventory planning. Facilities operating with narrow buffers or inflexible procurement arrangements face heightened exposure to cost swings, which in turn influences pricing stability for downstream buyers. This dynamic is particularly acute in regions where feedstock logistics and storage constraints amplify supply variability.
Challenge Three: Regulatory and Logistics Compliance Burden
Hazardous chemical handling introduces a compliance layer that touches production, storage, transportation, and labor practices. A meaningful share of manufacturers report increased compliance costs tied to storage regulations, while logistics providers face restrictions related to chemical transportation safety standards. Elevated labor and safety costs in production facilities further contribute to operating expense pressure. These factors are not marginal; they influence site selection, capacity expansion timing, and the cost of serving distant markets.
Key Drivers Behind Market Evolution
Growth in the VPA market is not accidental. It is being shaped by a set of reinforcing drivers that alter where value is created and how companies compete. Four forces stand out.
Technical Innovation and Purity Engineering
The most visible driver is the push toward higher purity and application-tuned specifications. Industry developments in 2024 and 2025 illustrate this direction. A high-purity 92 percent grade with 14 percent lower impurities was introduced, reflecting a strategic emphasis on impurity control as a differentiator. This matters because even modest reductions in trace contaminants can translate into improved performance in coatings, corrosion inhibition, and polymer modification. Innovation is increasingly less about new molecule discovery and more about precision manufacturing, analytical control, and specification reliability.
Phosphoric Acid Market
Policy and Regulatory Environment
Regulatory expectations around hazardous chemical storage and transportation continue to tighten. Rather than acting as a uniform brake, these requirements are reshaping competitive dynamics. Companies with mature compliance infrastructure, documented safety processes, and regional distribution capacity are better positioned to absorb regulatory friction. Conversely, organizations with fragmented logistics or limited safety investment face higher relative cost and longer time to market. In practice, compliance is becoming a selection criterion for buyers who need predictable supply and reduced operational risk in their own value chains.
Demand-Side Shifts Across Industrial and Specialty Applications
Demand is broadening but not evenly. Coatings remain a core consumption center, driven by performance needs in corrosion resistance, adhesion, and flame retardancy. Water treatment and oil well applications sustain steady demand linked to industrial infrastructure and resource extraction activity. Fuel cells represent a smaller but strategically important segment, where VPA’s functional properties support research and development pathways even if commercial scale remains nascent. Medical care and printing applications contribute niche volumes with distinct purity and handling requirements.
The common thread is not volume growth in isolation but specification sensitivity. Buyers are less interested in generic availability and more focused on whether a grade reliably meets performance thresholds in their process. This shifts purchasing decisions toward suppliers who can evidence consistency, provide technical support, and align product grades with application outcomes.
Supply Chain and Cost Structure Realignment
Supply chain design is becoming a strategic variable. Regional distribution optimization has reduced delivery lead times by 21 percent across three regional distribution centers for one manufacturer, a change that directly affects service levels and inventory planning for downstream customers. At the same time, upstream feedstock fluctuations continue to drive raw material volatility, influencing production economics. Together, these factors are pushing companies to balance proximity, redundancy, and cost efficiency more deliberately. Supply chains that can flex across regions while maintaining specification integrity are gaining a practical advantage.
Competitive Landscape and Leading Strategies
The competitive structure of the VPA market is moderately concentrated, with the top three players accounting for approximately 28.5 percent of revenue and the top five reaching roughly 35.2 percent. This level of concentration indicates that while no single company controls the market, a small group of established players sets much of the pace in specification development, regional coverage, and compliance posture. The rest of the market is dispersed among regional suppliers, specialty producers, and laboratory-focused vendors, creating a multi-layered landscape rather than a simple oligopoly.
Strategic Positioning Among Leading Companies
Several firms illustrate the different ways competition is being structured.
- One German-based producer emphasizes high-purity VPA in both 80 percent and 90 percent grades, with ISO 9001 certification and a portfolio covering monomer and polymer grades for coatings, corrosion inhibition, flame retardancy, and adhesion. Its positioning centers on specification breadth and certified quality control, which supports use across multiple industrial functions.
- A major European chemical company offers specialty VPA grades aimed at polymer modification, coatings, and water treatment. Its advantage lies in the ability to slot VPA into broader specialty chemical portfolios and leverage existing customer relationships in performance materials and water-related applications.
- A Brussels-based supplier provides VPA grades including a formulation for aluminum pretreatment and corrosion inhibition. Its differentiation is application-solving rather than generic supply, targeting a specific industrial pretreatment need with a branded grade.
- A Tokyo-headquartered chemical supplier markets VPA as a high-purity liquid for laboratory and specialty chemical synthesis. Its role is narrower, serving R&D, pilot-scale, and specialty synthesis demand where purity and traceability matter more than bulk cost.
- An Italian manufacturer focuses on VPA for industrial and pharmaceutical applications, indicating a dual-use orientation that spans conventional industrial demand and higher-specification pharmaceutical relevance.
These profiles show that leadership is not defined by a single formula. Some players win through certified quality and grade variety, others through application-specific formulation, and others through purity and technical service for specialized users.
Differentiation Levers and Recent Moves
In a market where volume is constrained and performance requirements are rising, differentiation tends to appear in three levers: purity and impurity control, application reliability, and service responsiveness. Recent industry developments reinforce this pattern. The introduction of a 92 percent high-purity grade with lower impurities reflects a purity-driven differentiation strategy. The reduction in delivery lead times through regional distribution optimization shows a service-level differentiation strategy that improves reliability for buyers. Meanwhile, upgraded polymer modification testing facilities in Asia-Pacific have increased quality assurance throughput by 25 percent, pointing to investment in process verification and application readiness.
These moves matter because they align with how buyers purchase in specialty chemicals. In coatings and water treatment, batch consistency and impurity control affect end-product performance. In polymer modification, testing throughput and quality assurance affect the speed at which new formulations can be validated. In laboratory and specialty synthesis, purity and documentation support downstream reproducibility. Companies that invest in these levers are not simply selling a chemical; they are selling predictable outcomes.
Market Structure Evolution
The market is likely to evolve along two concurrent paths: selective consolidation and continued niche segmentation. Consolidation will probably remain measured rather than aggressive. Because VPA serves multiple applications with different specification needs, scale alone does not guarantee advantage. However, companies that can combine purity control, compliance readiness, and regional distribution capacity are well placed to acquire share from smaller competitors that lack one or more of these capabilities.
At the same time, segmentation will persist. Laboratory-grade supply, industrial bulk grades, and specialized pretreatment or polymer modification grades each carry different buyer expectations, pricing logic, and service requirements. New entrants are most likely to appear in niche positions where a specific grade, regional service advantage, or technical support capability can create a defensible position without requiring dominant scale. The practical outcome is a market that becomes more tiered, with premium specification players, application-focused specialists, and cost-oriented regional suppliers coexisting.
Strategic Outlook for the Next Three to Five Years
Looking ahead to 2032, three trends are likely to shape commercial opportunity and risk.
Trend One: Purity and Specification As control Become the Default Expectation
As higher-purity grades become more widely available and application performance expectations rise, what is considered acceptable purity will shift upward across more use cases. This will compress the middle ground where generic, lower-specification supply once found a home. Suppliers will need to demonstrate tighter impurity control, stronger analytical documentation, and consistent lot performance. The commercial opportunity lies in grades and services that reduce downstream processing variability, especially in coatings and polymer modification, where small quality differences can have outsized effects on end-use performance.
Trend Two: Regional Service Networks Will Matter More Than Raw Proximity
Lead-time reduction, regional distribution optimization, and improved delivery reliability are becoming competitive differentiators. Buyers increasingly value predictable timing and service consistency as much as unit price, particularly when chemical handling and logistics constraints raise the cost of disruption. Companies that build or strengthen regional service networks will be better positioned to capture share in markets where responsiveness and safety compliance are closely linked. This trend also creates opportunities for partnerships that improve storage, transportation, and inventory buffering without requiring every producer to own the full logistics chain.
Trend Three: Regulatory Friction Will Elevate Compliant Operators
Compliance costs tied to hazardous chemical storage, transportation safety standards, and elevated labor and safety requirements are unlikely to recede. Instead, they will continue to separate operators that have built institutional capability from those that have not. Over the next few years, this will influence which producers can expand efficiently, which can serve certain regions reliably, and which can maintain stable pricing. The strategic opportunity is to treat compliance as part of the value proposition rather than a cost to minimize in isolation. Buyers in sensitive applications may prefer suppliers whose safety and transport readiness lower their own operational exposure.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Feedstock volatility remains a persistent risk; if phosphorus-based feedstock supply fluctuations intensify, production economics could tighten and pricing volatility could increase. Regulatory changes could further raise storage and transportation requirements, reshaping cost structures and market access. Demand may also shift faster than expected in certain applications, particularly where alternative materials, formulation changes, or new process technologies reduce reliance on VPA in specific functions. Finally, capacity additions in Asia-Pacific and other regions could alter supply balance, intensifying competition in some segments while creating export opportunities in others.
Actions for Decision-Makers
The VPA market rewards companies that align their strategy with specification sensitivity, service reliability, and compliance readiness. The following actions are most relevant across different roles.
Phosphonate Market
For Manufacturers and Producers
- Prioritize purity engineering and analytical consistency over undifferentiated capacity expansion. In a market where higher-purity grades and lower impurity levels are gaining traction, the ability to document and replicate performance will shape pricing power and customer retention.
- Invest in regional distribution and lead-time reliability. Reducing delivery friction is not just a logistics improvement; it is a commercial differentiator that supports premium positioning and reduces the likelihood of substitution under pressure.
- Design compliance into operations as a competitive asset. Storage, transportation, and labor safety costs are real, but companies that manage them systematically can use reliability and risk reduction as part of their customer value proposition.
For Investors and Strategic Partners
- Focus on business models that combine specification control with service differentiation rather than volume alone. The strongest growth potential lies in companies that can secure long-term relationships through purity, consistency, and responsiveness, especially in coatings, water treatment, and polymer modification.
- Watch for selective consolidation opportunities where regional or specialty players lack the compliance infrastructure, analytical capability, or distribution reach to compete upward. Value creation may come more from capability alignment than from scale expansion.
- Monitor feedstock exposure and regional capacity dynamics. Margins and pricing stability will depend on how well companies manage raw material volatility and adapt to shifting supply balance across regions.
For Procurement and Supply Chain Leaders
- Evaluate suppliers on specification reliability and service consistency as well as price. In applications where impurity levels and batch consistency affect performance, the lowest headline price may not translate into the lowest total cost if variability creates processing risk.
- Build buffer and logistics strategies that account for hazardous chemical transportation constraints. Where safety standards and transport restrictions raise the cost of disruption, regional distribution capability and documented handling practices can reduce supply risk.
- Align grade selection with application outcomes. The choice between 80 percent, 90 percent, and higher-purity grades should be tied to actual performance requirements and downstream process sensitivity, not just inventory convenience.
The commercial dynamics of vinylphosphonic acid are increasingly defined by precision, service, and compliance rather than by bulk commodity logic. For companies operating in coatings, water treatment, polymer modification, fuel cells, medical care, printing, and related specialty segments, the window to strengthen positioning is now, before specification expectations and regulatory expectations become even more firmly entrenched. Detailed segmentation data, regional breakdowns, grade-level dynamics, and customized scenario analysis are available in the full PW Consulting report on the Vinylphosphonic Acid Market, which provides the deeper quantitative and strategic detail needed for planning beyond high-level trends.
For detailed analysis of this topic, please visit the official page: Vinylphosphonic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Bike Market 2026: 10.54% CAGR Trajectory and the Asia Pacific Shift
By PW Consulting, 2026-09-21
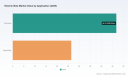
Electric Bike Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The electric bike market has transitioned from a niche alternative to a mainstream mobility solution, demonstrating sustained expansion over the past five years. Between 2020 and 2025, industry revenue climbed from approximately 41.9 billion USD to 73.2 billion USD, reflecting a compound annual growth rate that underscores the sector's resilience and accelerating adoption. Forward projections indicate continued momentum, with revenue expected to reach 147.2 billion USD by 2032, translating to a CAGR of 10.54 percent across the 2026-2032 forecast horizon. This trajectory positions electric bikes as one of the fastest-growing segments within the broader micro-mobility and personal transportation landscape, driven by urbanization pressures, sustainability mandates, and evolving consumer preferences for flexible, low-emission transit options.
Despite the robust growth trajectory, the industry stands at a critical inflection point where several structural challenges threaten to reshape competitive dynamics. First, regulatory fragmentation is intensifying across key markets. Jurisdictions are diverging on speed limits, motor power thresholds, battery safety mandates, and classification frameworks, creating compliance complexity for manufacturers operating across multiple regions. Second, raw material volatility is introducing cost uncertainty, particularly in battery component pricing, which directly impacts margin structures and pricing strategies. Third, market concentration remains relatively high, with the top three players holding a substantial share of global revenue and the top five firms commanding an even larger portion, which raises barriers to entry and compresses differentiation opportunities for smaller competitors. These forces collectively demand strategic agility from market participants seeking to capture growth without exposing themselves to excessive regulatory, cost, or competitive risk.
Key Drivers Shaping Market Evolution
Technological Innovation and Performance Differentiation
Technology remains the primary engine of market expansion, with advancements in motor efficiency, battery energy density, and smart connectivity reshaping product expectations. Manufacturers are increasingly embedding proprietary control units, GPS tracking, over-the-air updates, and integrated app ecosystems into their platforms. These features extend beyond novelty; they address safety concerns, enable fleet management capabilities, and create recurring engagement loops that strengthen brand loyalty. Recent model launches illustrate this trajectory: one U.S.-based brand introduced a fat-tire model with enhanced range and a proprietary control unit supporting GPS and OTG functionality, signaling how connectivity and utility features are becoming baseline expectations rather than premium add-ons. Simultaneously, performance-oriented manufacturers are pushing torque outputs and frame materials to cater to aggressive riding styles and demanding terrain, while other players focus on step-through designs and extended range to serve senior and recreational segments. The technological arms race is widening product segmentation and forcing companies to clarify whether they compete on accessibility, performance, or integrated digital experience.
Policy and Regulatory Environment as a Market Accelerant and Constraint
Policy frameworks are actively reshaping demand patterns and compliance requirements. In the United States, reciprocal tariffs on Chinese electric bicycle imports were reduced from 55 percent to 45 percent effective November 2025, easing some cost pressures on imported finished goods while still maintaining a significant trade barrier. This adjustment alters sourcing economics and encourages regional assembly or supply chain diversification strategies. Concurrently, California implemented updated State Fire Marshal safety standards for electric bike batteries effective January 2026, requiring manufacturers to demonstrate enhanced thermal management and certification compliance. In Europe, the European Commission fully enforced the revised EN 15194 standard after August 2025, harmonizing technical requirements but also tightening conformity assessment processes. Meanwhile, the United Kingdom revoked anti-dumping duties on non-folding electric bikes of Chinese origin in February 2025, opening a pathway for cost-competitive imports in that segment. Collectively, these regulatory shifts are creating a patchwork environment where successful players must navigate divergent safety, classification, and trade rules while leveraging favorable policy windows to optimize cost structures.
Demand-Side Shifts in Urban Mobility and Commercial Utility
Consumer and enterprise behavior is evolving beyond recreational use toward practical, daily mobility solutions. City and urban applications continue to dominate usage patterns, reflecting the role of electric bikes in first-mile and last-mile connectivity, commute substitution, and congestion avoidance. At the same time, cargo and utility applications are gaining meaningful traction as businesses and households recognize the cost and efficiency advantages of electric cargo bikes for local deliveries, family transport, and municipal operations. This shift is reinforced by rising fuel costs, parking constraints, and corporate sustainability targets that incentivize fleet electrification at the micro-mobility level. Demand is also becoming more segmented by rider profile: high-performance models appeal to enthusiasts and trail riders, while accessible step-through designs and folding formats attract seniors, multi-modal commuters, and space-constrained urban users. These diverging demand clusters require manufacturers to align product architecture, marketing positioning, and distribution channels with specific use cases rather than relying on generic electric bike positioning.
Supply Chain and Cost Structure Dynamics
The supply chain environment is undergoing a period of recalibration as material costs, logistics constraints, and sourcing strategies interact. Lithium carbonate prices rose sharply in December 2025 and January 2026, with industrial grades increasing by double-digit percentages, placing upward pressure on battery pack costs and, by extension, finished product pricing. This volatility highlights the sensitivity of margin profiles to commodity cycles and underscores the value of long-term supplier agreements, battery chemistry diversification, and design efficiencies that reduce dependency on constrained inputs. At the same time, tariff adjustments and trade remedy decisions are prompting companies to reconsider manufacturing footprints, assembly locations, and inventory strategies. Some manufacturers are responding by emphasizing regional distribution, localized assembly partnerships, or product architectures that optimize shipping efficiency and tariff exposure. The net effect is a market where cost discipline and supply chain resilience are becoming as strategically important as product features in determining competitive outcomes.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of regional specialists, performance-focused incumbents, and accessible-value brands, each pursuing distinct strategic positioning. Premium German manufacturers have built strong reputations around integrated drive systems, advanced battery integration, and high-end frame engineering, targeting customers who prioritize durability, ride quality, and ecosystem alignment with established component suppliers. These firms compete on engineering credibility and residual value, often anchoring their portfolios in eMTB, cargo, and city categories with sophisticated powertrain integration. U.S.-based brands occupy a broad value spectrum, ranging from budget-friendly folding and cruiser models with emphasis on quiet operation and certified electrical safety, to mid-range and premium platforms that differentiate through proprietary app controls, GPS tracking, and over-the-air update capabilities. This stratification allows American manufacturers to address price-sensitive urban riders as well as tech-conscious consumers seeking connected features. Global players such as hybrid bike leaders and Taiwanese high-end manufacturers leverage scale, alloy frame expertise, and battery option flexibility to serve commuter and performance segments with broad geographic reach. A Dutch specialist has carved out a niche in compact folding designs with efficient pedal-assist systems, targeting urban mobility users who prioritize portability and maneuverability.
Recent product activity reinforces the intensity of differentiation. A U.S. brand expanded its fat-tire lineup with enhanced range and GPS/OTG functionality, reinforcing its focus on connected adventure and urban versatility. A Taiwanese manufacturer introduced new eMTB series powered by Bosch CX motors in alloy frames, emphasizing improved affordability while maintaining performance credibility. A major global brand launched a flagship model with a carbon frame and high torque output, signaling continued investment in premium performance segments. These moves illustrate how leaders are contesting multiple battlegrounds simultaneously: range and battery endurance, motor torque and frame material, connectivity and software integration, and price-to-performance ratios across accessibility and premium tiers.
The market structure is evolving along two parallel paths. Consolidation is likely to accelerate among mid-tier players seeking scale, distribution leverage, and cost efficiencies, particularly as compliance and battery cost pressures raise the fixed-cost threshold for sustained competitiveness. At the same time, fragmentation persists in specialized niches such as cargo utility, folding urban formats, senior-focused accessibility designs, and high-performance trail categories, where targeted product architecture and community-driven branding can sustain differentiation. New entrants are most likely to succeed by focusing on underserved use cases, regional compliance advantages, or digital service ecosystems rather than attempting to compete broadly on hardware alone. Companies that combine clear segmentation, disciplined cost structures, and defensible feature sets are best positioned to navigate this environment.
Electric Bicycles Market
Strategic Trends and Outlook for 2026-2032
Several trends are likely to define the market over the next three to five years. First, connectivity and software-defined features will become increasingly central to product value propositions. As GPS tracking, app-based controls, and over-the-air updates move from differentiators to expectations, manufacturers that treat the electric bike as a platform with ongoing digital engagement will have an advantage in retention, service revenue, and fleet integration. This trend creates opportunities for brands that can build reliable software stacks, secure update pathways, and data-informed rider experiences without compromising electrical safety or user privacy.
Second, regulatory alignment and battery safety certification will increasingly shape market access and sourcing decisions. As jurisdictions tighten battery standards and harmonize technical requirements, companies with robust quality assurance processes and transparent compliance documentation will face fewer market entry frictions. The trend also opens opportunities for suppliers and assemblers that can deliver certified battery systems with traceable sourcing and consistent performance. However, the risk lies in uneven enforcement and periodic standard revisions that can disrupt product roadmaps and require rapid design adjustments.
Third, cargo and utility applications are expected to expand beyond early adopters into broader commercial and household use. Local delivery operators, municipal programs, and multi-purpose household users are likely to increase adoption as total cost of ownership advantages become more apparent and as frame, battery, and load-capacity designs improve. This trend presents opportunities for purpose-built cargo architectures, swappable battery configurations, and service networks tailored to commercial uptime requirements. The associated risk is that utility-focused models must withstand higher usage intensity, which places greater demands on component durability, warranty management, and after-sales support.
Underlying these trends are unresolved uncertainties. Commodity price swings can quickly alter margin assumptions, and tariff or trade-remedy shifts may change the cost competitiveness of imported versus regionally assembled products. Demand could also diverge by region if economic conditions affect discretionary spending or if public transport investments alter commute substitution dynamics. Manufacturers and investors should therefore treat growth as achievable but contingent on strategic choices around sourcing, compliance, segmentation, and service infrastructure.
Electric Motorcycle Market
Actionable Recommendations for Decision Makers
For manufacturers, the priority is to reinforce product architecture decisions with clear segmentation and compliance readiness. Rather than broadening portfolios indiscriminately, companies should define whether they compete on accessible value, performance credibility, or connected digital experience, and then align motor, battery, frame, and software choices accordingly. Investing in battery safety certification, traceable sourcing, and design efficiencies that reduce exposure to commodity volatility will help protect margins and ensure continuity across regulatory cycles. Manufacturers should also evaluate assembly and distribution footprints against tariff exposure and shipping efficiency, especially as trade conditions remain fluid. Building proactive after-sales and service capabilities is equally important, particularly for cargo and utility models where uptime and durability directly influence commercial adoption.
For investors, the opportunity lies in identifying players with defensible segmentation, resilient cost structures, and scalable digital or service propositions. Due diligence should extend beyond top-line growth to assess battery supply agreements, certification readiness, tariff sensitivity, and the credibility of software and connectivity roadmaps. Companies that combine clear use-case positioning with disciplined manufacturing and compliance practices are more likely to sustain margins and navigate consolidation pressures. Investors should also monitor regions where regulatory changes create temporary cost advantages or new import pathways, as these conditions can reshape competitive positioning over short to medium horizons.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet decision makers, the focus should be on total cost of ownership, safety compliance, and operational fit rather than upfront price alone. Evaluating battery certification status, warranty structures, service network coverage, and load-capacity suitability for specific urban or cargo tasks will reduce operational risk and support longer asset life. Organizations deploying electric bikes at scale should consider standardized battery and component specifications where possible, while preserving enough flexibility to match different rider profiles and route requirements. Procurement teams should also track regulatory updates in their operating jurisdictions, as changing safety and classification standards can affect model availability, replacement part compatibility, and compliance timelines.
For decision makers seeking deeper granularity on regional demand patterns, segment-level sizing, pricing dynamics, and company-specific competitive benchmarks, the full research report provides detailed quantitative breakdowns and customized strategic guidance. Accessing that level of detail can help narrow strategic options, stress-test sourcing and compliance plans, and prioritize investments in the segments most aligned with specific business objectives.
For detailed analysis of this topic, please visit the official page: Electric Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silver-based Antimicrobial Agent Market: What 6.98% CAGR Means for 2032 Growth
By PW Consulting, 2026-09-21
The Silver-Based Antimicrobial Agent Market: Navigating Growth, Regulation, and Strategic Opportunities Through 2032
The silver-based antimicrobial agent market has evolved from a niche specialty segment into a structurally significant component of the broader biocides and functional materials landscape. Between 2020 and 2025, global revenue expanded from approximately USD 153.44 million to USD 215.0 million, reflecting a compound trajectory shaped by sustained infection-control priorities, material-performance demands, and incremental substitution against conventional chemical biocides. Looking ahead to 2032, the market is projected to reach USD 344.79 million, underpinned by a forecast-period CAGR of 6.98%. This growth rate signals steady, technology-led expansion rather than speculative boom dynamics, making it a market where disciplined positioning, regulatory fluency, and application-specific differentiation will separate long-term winners from cyclical participants.
PW Consulting Health Care Research Center
Despite the positive directional signal, the sector operates at a critical inflection point. Three structural challenges are reshaping how manufacturers, formulators, and end-users approach silver-based antimicrobial solutions. First, feedstock volatility has moved from a background concern to a core planning variable. Silver prices climbed sharply through 2024 and 2025, reaching roughly $50 per ounce amid converging industrial demand pressures, which directly elevated the cost base for silver nitrate and related precursors. Second, regulatory gatekeeping is tightening across major end markets. In the United States, EPA registration requirements for silver or silver-ion applications in textiles now demand rigorous safety, efficacy, and environmental-impact documentation, adding time and compliance cost to product development cycles. Third, downstream sustainability mandates are rewriting formulation rules. China’s Recycled Plastics Standards (GB/T 45091-2024), effective from June 2025, introduced restricted-substance guidelines for antimicrobial additives in recycled polymer streams, forcing suppliers to demonstrate compatibility with circularity goals rather than simply delivering antimicrobial performance. Together, these forces are compressing the window for undifferentiated commodity offerings and elevating the value of technically validated, regulation-ready, and application-optimized products.
Technical Innovation and Carrier Architecture
The most consequential driver of market evolution is not silver itself but the carrier systems that control ion release, durability, and compatibility. Silicate-based carriers continue to anchor a large share of the market because they offer a balanced combination of sustained antimicrobial activity, thermal stability, and processing flexibility across polymers and coatings. Phosphate-based carriers occupy a complementary role where controlled reactivity and specific substrate interactions are prioritized, while titanium dioxide carrier systems are gaining relevance in applications that pair antimicrobial function with photocatalytic or surface-modification benefits. The strategic implication is clear: competitive advantage is shifting from raw silver content to engineered release kinetics, particle morphology, and formulation compatibility. Companies that can demonstrate predictable performance across extrusion, coating, or textile-finishing processes are capturing premium positioning, while those relying on generic silver inputs face margin pressure and heightened customer qualification hurdles.
Regulatory Architecture as a Market Filter
Regulation is no longer a peripheral compliance cost; it functions as a market filter that shapes entry dynamics, product architecture, and go-to-market pacing. EPA registration for silver-based applications in U.S. textiles has raised the evidentiary bar for safety, efficacy, and environmental impact, making regulatory readiness a de facto competitive requirement. At the same time, China’s updated recycled-plastics standards have intensified scrutiny on restricted substances, pushing formulators to align antimicrobial additives with broader material-circularity expectations. For market participants, this means that product pipelines must be built with regulatory trajectory in mind, not simply current technical performance. Early alignment with testing protocols, documentation standards, and regional substance restrictions reduces time-to-market risk and strengthens customer trust, particularly in applications where compliance failures can disrupt entire supply chains.
Demand-Side Shifts and Application Expansion
Demand is being reshaped by a blend of consumer behavior, institutional procurement standards, and functional-material expectations. Textiles remain a dominant application environment, where antimicrobial and odor-control performance supports hygiene-sensitive use cases, performance apparel, and institutional fabric programs. Beyond textiles, coatings and plastics are expanding the addressable surface area for silver-based antimicrobials, particularly where long-lasting protection, surface durability, and low-maintenance operation are valued. Consumer and enterprise buyers increasingly evaluate antimicrobial features not as isolated add-ons but as part of broader product reliability, sustainability, and lifecycle narratives. This shift rewards solutions that can be integrated without compromising material properties, appearance, or recyclability, and it penalizes formulations that create processing friction or end-of-life complications.
Supply-Side Dynamics and Cost Structure
On the supply side, the market is navigating the intersection of precious-metal economics and industrial chemistry. Silver nitrate export prices displayed notable volatility in mid-2025, influenced by Asian production declines and feedstock-level dynamics, reinforcing the need for procurement agility and formulation efficiency. Manufacturers are responding by optimizing carrier loadings, improving dispersion and ion-release efficiency, and diversifying source strategies where feasible. The broader implication is that cost leadership in this market is increasingly derived from process efficiency and application engineering rather than from raw-material arbitrage alone. Companies that can maintain performance while reducing effective silver intensity, or that can offer stable pricing through long-term supply arrangements and technical service support, are better positioned to retain customers through cycles of input-cost volatility.
Strategic Positioning Among Leading Players
The competitive landscape remains moderately consolidated, with the top three participants holding roughly 24.6% of market revenue and the top five reaching approximately 26.2%. This concentration suggests a market where scale, application breadth, and technical service networks matter, but where meaningful space still exists for specialized players with strong formulation expertise or regional execution capabilities. Leading participants are differentiating along several axes. Some emphasize inorganic silver carrier technologies purpose-built for water treatment, polymers, and resins, positioning around durability and controlled release. Others focus on silver-based additives for textiles, plastics, and coatings, integrating antimicrobial functionality into broader material portfolios. A further group targets disinfectant and hygiene applications through silver-based chemistries such as silver dihydrogen citrate, highlighting food-hygiene and surface-sanitation use cases. There is also notable activity around glass-carrier and inorganic silver systems, where the emphasis is on stability and compatibility in demanding material environments. Rather than competing solely on price, the more defensible strategies combine application-specific validation, regulatory documentation, and technical support that lowers integration risk for customers.
Antimicrobial Peptides Market
M&A, Portfolio Shaping, and New-Entry Dynamics
Recent corporate activity signals an ongoing reshaping of portfolios around silver-based antimicrobial capabilities. BASF’s completion of the Aseptrol biocide business transaction with Oxidium Technologies LLC, including silver-based antimicrobial solutions, illustrates how large chemical and biocides players are consolidating functional-material assets to strengthen application coverage and technology breadth. At the same time, PURE Bioscience’s brand repositioning around its silver dihydrogen citrate technology for food hygiene reflects a strategic attempt to sharpen market identity and align product messaging with specific end-use priorities. These moves point to a broader pattern: incumbents are tightening their focus around differentiated technology platforms, while the entry of new players is likely to occur through targeted application niches, regional distribution partnerships, or specialized carrier chemistry rather than through broad commodity competition. The practical consequence is an environment where customer qualification, regulatory readiness, and proven integration performance increasingly determine market access.
Forecast Trends and Commercial Implications
Over the next three to five years, three interlocking trends are likely to define how value is created in this market. First, application engineering will become the primary battleground. As carrier technologies mature, differentiation will depend on how well antimicrobial performance is maintained across specific processing conditions, substrates, and end-use environments. Companies that invest in application-level validation and offer formulation guidance will capture more resilient demand than those selling generic functional ingredients. Second, regulatory and sustainability integration will move from a compliance exercise to a product-design input. Documentation readiness, restricted-substance alignment, and compatibility with recycled or circularity-driven material flows will influence purchasing decisions, especially among multinational buyers and regulated-industry customers. Third, input-cost volatility will continue to reward efficiency and service depth. Pricing pressure from silver feedstock fluctuations will likely persist, but customers will increasingly prefer partners who can stabilize total cost of ownership through technical optimization, predictable supply, and quality assurance rather than chasing the lowest nominal price point.
These trends translate into tangible commercial opportunities. There is room for growth in high-value application segments where antimicrobial durability and regulatory confidence carry premium value, especially in hygiene-sensitive textiles, performance coatings, and specialized polymer applications. There is also opportunity for suppliers that can provide regionally compliant documentation packages and application-specific testing support, reducing the burden on formulators and procurement teams. At the same time, uncertainty remains. Silver price trajectories, regulatory tightening in key markets, and evolving standards for recycled-content materials could alter relative competitiveness across carrier types and end-use segments. Participants should therefore avoid overcommitting to a single application or carrier architecture without scenario planning for regulatory shifts and feedstock volatility.
Strategic Actions for Manufacturers
For manufacturers and formulators, the priority is to treat silver-based antimicrobial ingredients as engineered system components rather than commoditized additives. That means validating performance under actual processing conditions, building regulatory documentation early, and aligning product design with downstream sustainability requirements. Where possible, optimize carrier loading and ion-release efficiency to protect performance while managing silver intensity. Strengthening technical-service capabilities can also create a durable moat, because customers increasingly value partners who reduce integration risk and accelerate qualification cycles.
Worldwide Smart Antimicrobial Surface Market
Strategic Actions for Investors
For investors, the market offers attractive structural growth, but returns will likely accrue to platforms with defensible application breadth, regulatory readiness, and disciplined feedstock management. Due diligence should focus on the quality of carrier technology, the strength of application validation, and the ability to navigate regional compliance requirements. Visibility into customer concentration, product qualification pipelines, and exposure to silver-input volatility is essential when evaluating long-term resilience. Companies that can demonstrate recurring demand from regulated or hygiene-critical applications are better positioned than those reliant on discretionary or price-sensitive volume.
Strategic Actions for Procurement and Sourcing Leaders
For procurement and sourcing leaders, the strategic task is to balance cost, compliance, and performance stability. Multi-source planning, clear specification of required antimicrobial performance and regulatory documentation, and evaluation of supplier technical support can reduce exposure to both price volatility and compliance disruption. Where applications are regulated or publicly visible, prioritizing suppliers with established registration footprints and robust testing packages can lower downstream risk. In parallel, procurement teams should monitor changing restricted-substance and recycled-material standards to avoid specification mismatches that could affect product acceptability.
The silver-based antimicrobial agent market is entering a phase where informed, application-aware decision-making matters more than ever. Growth is supported by durable demand in hygiene-sensitive and performance-driven applications, but the payoff will go to participants who can integrate technical, regulatory, and supply-side realities into coherent commercial strategies. For executives and planners seeking detailed segmentation data, regional and application-level revenue splits, competitive benchmarking, and scenario-based forecasts, a full research report can provide the granularity needed to translate these market dynamics into specific sourcing, investment, and product-development decisions.
For detailed analysis of this topic, please visit the official page: Silver-based Antimicrobial Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Silicon Monoxide Market: Why 15.1% CAGR Reshapes Automotive & Electronics Demand
By PW Consulting, 2026-09-21
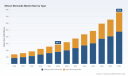
Silicon Monoxide Market: Strategic Trends and Commercial Opportunities (2025–2032)
The silicon monoxide market has entered a phase of accelerated expansion, driven by converging demands across advanced electronics, energy storage, and industrial coatings. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenues climbing from approximately $141 million to $285 million. This trajectory is projected to continue through the forecast period ending in 2032, with an estimated compound annual growth rate of 15.1 percent. By the close of the decade, the market is expected to surpass $760 million, reflecting a structural shift rather than a cyclical upswing. The growth is not uniform across all verticals or geographies; it is concentrated in application areas where material purity, thermal stability, and barrier properties are becoming critical differentiators.
For executives and investors tracking specialty materials, this market presents a compelling case study in how a relatively niche inorganic compound is transitioning into a strategic enabler for multiple high-growth industries. The challenge lies in navigating a fragmented supply base, evolving regulatory frameworks, and rapidly changing end-user specifications. Understanding where value is being created—and where vulnerabilities are emerging—requires moving beyond headline figures to examine the underlying technological, policy, and supply chain dynamics.
Market Status and Core Challenges
The current market structure reflects a balance between established industrial uses and emerging high-performance applications. Gaseous and solid forms of silicon monoxide serve distinct processing requirements, with each format catering to specific deposition, coating, or synthesis workflows. The revenue split between these formats underscores a mature but still evolving production ecosystem, where manufacturers are increasingly pressured to deliver consistent purity levels while scaling output. Similarly, demand is distributed across automotive and transportation, consumer electronics, energy and power systems, and a range of secondary applications. This distribution signals that no single industry dominates the growth narrative; instead, multiple sectors are pulling the market forward, each with its own technical thresholds and procurement cycles.
Geographically, the market exhibits a multi-polar character. North America, Europe, and Asia Pacific each command significant shares, while Latin America and the Middle East and Africa represent smaller but gradually expanding footholds. This geographic spread is not merely a reflection of historical manufacturing capacity; it is increasingly shaped by localized supply chain strategies, trade flows, and regional industrial policies. The presence of verified exporters across multiple continents, alongside targeted trade activity in emerging markets, indicates that silicon monoxide is moving through a globalization phase where sourcing flexibility and regulatory compliance are becoming as important as price competitiveness.
Several structural challenges complicate this growth trajectory.
- Purity and consistency requirements are intensifying. As silicon monoxide finds its way into battery anodes, thin-film deposition, and high-barrier packaging, end users are demanding tighter control over impurities and particle morphology. Inconsistent feedstock quality or variable reaction conditions can disrupt downstream performance, making quality assurance a competitive moat rather than a baseline expectation.
- Regulatory and trade compliance is fragmenting. Classification under inorganic compound duty frameworks, coupled with shifting export documentation requirements and country-specific trade data reporting, adds layers of complexity for cross-border procurement. Companies that treat compliance as an afterthought face delays, cost overruns, and potential supply interruptions.
- Supply chain concentration risks are emerging. While the market remains relatively fragmented at the top, with the top three and top five players holding modest combined shares, the underlying production ecosystem depends on high-temperature reaction processes and reliable silicon feedstock. Any disruption in upstream material availability or energy-intensive manufacturing capacity can create bottlenecks that ripple through multiple application sectors.
For decision makers, these challenges are not merely operational headaches; they are strategic inflection points. Companies that proactively address purity standardization, trade compliance, and feedstock resilience will be better positioned to capture premium segments, while those that compete primarily on price risk margin compression as customer expectations rise.
Key Demand Drivers Analysis
Technological Innovation and Material Breakthroughs
The most powerful accelerator for silicon monoxide demand is the ongoing push toward higher-performance materials in energy storage and electronic fabrication. In lithium-ion battery development, silicon-based anodes are attracting sustained attention for their potential to increase energy density compared with conventional graphite formulations. Silicon monoxide plays a role in this ecosystem both as a precursor and as a functional component in coating and synthesis workflows. Manufacturers that can deliver high-purity forms tailored to anode development are aligning themselves with a long-term technological shift rather than a short-term procurement trend.
At the same time, vacuum deposition and sputtering applications continue to rely on silicon monoxide evaporation sources and related deposition materials. As thin-film processing becomes more precise in semiconductor-adjacent and industrial coating environments, the need for stable evaporation behavior, predictable particle size, and reproducible deposition rates is increasing. This is driving suppliers to refine product forms—pieces, powders, and customized evaporation sources—so that downstream users can reduce process variability and improve yield.
Policy and Regulatory Environment
Regulatory conditions are shaping market access and cost structures in subtle but meaningful ways. In key markets such as the United States, silicon monoxide is classified under inorganic compound duty frameworks that generally allow duty-free treatment, lowering the tariff barrier for cross-border trade. While this may appear to be a minor detail, it has practical implications for sourcing strategies, especially for manufacturers that operate across multiple jurisdictions or assemble final products from globally sourced components.
Beyond tariffs, export documentation and trade transparency are becoming more prominent. Verified export activity across multiple shippers and destinations over recent periods indicates that the trade network is active but still relatively dispersed. For companies engaged in import/export operations, the ability to navigate shipment verification, country-of-origin documentation, and destination-specific requirements is increasingly a differentiator. Regulatory clarity can reduce lead times and working capital friction, while ambiguity can create hidden costs that erode competitiveness.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user behavior is changing on two fronts. In consumer electronics, the drive toward smaller, more durable, and better-protected devices is reinforcing interest in barrier materials and thin-film coatings where silicon monoxide can contribute. In industrial and energy sectors, procurement teams are increasingly evaluating materials not just on specification sheets but on total cost of ownership, including process stability, waste reduction, and integration ease. This shift is pushing suppliers to offer more than raw material; it is encouraging value-added formats, technical support, and application-specific packaging.
The automotive and transportation segment reflects a broader transition toward electrification and lightweighting, where material performance and supply reliability matter more than ever. As vehicle manufacturers and their tier suppliers reassess component sourcing in response to electrification roadmaps and regional content requirements, silicon monoxide’s role in battery-related workflows and specialized coatings positions it as a material worth monitoring in procurement strategies.
Supply Chain and Cost Structure Evolution
The production of silicon monoxide typically involves high-temperature reactions between silicon and silicon dioxide, or carbon-based reduction of silicon dioxide, with high-purity silicon feedstock underpinning consistent quality. This process architecture means that energy costs, feedstock availability, and reaction control are central to margin dynamics. As energy markets fluctuate and industrial energy efficiency becomes a broader corporate priority, producers that can optimize thermal processes, reduce waste, and maintain tight purity control will gain an advantage.
At the same time, the supply base is expanding in certain regions, with manufacturers offering silicon monoxide pieces, powders, and chemical-grade products for coating and inorganic chemical portfolios. This diversification increases buyer options but also raises the importance of qualification and vendor evaluation. Buyers that build rigorous technical assessment processes can secure better terms and more reliable supply, while those that rely on spot purchasing without technical due diligence may encounter inconsistent performance.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of specialized producers, broad-line material suppliers, and regional manufacturers targeting distinct application niches. Rather than competing as a single undifferentiated market, participants are carving out positions based on purity ranges, product forms, application alignment, and geographic reach.
Several companies illustrate the strategic diversity currently shaping the market.
- Osaka Titanium Technologies Co., Ltd. has positioned itself around high-purity silicon monoxide for food packaging barrier applications and lithium-ion battery anode development. This dual focus reflects a strategy of linking material quality to high-value downstream uses, where purity and consistency directly influence customer outcomes.
- RD Mathis Company concentrates on evaporation sources, pieces, and deposition materials for vacuum technology. Its approach emphasizes process enablement, supplying the forms and configurations that deposition users need to reduce setup complexity and improve reproducibility.
- American Elements offers silicon monoxide in multiple purities and forms for research, sputtering targets, and industrial applications. This breadth-based model appeals to customers who require flexibility across R&D and production environments, and who value a supplier capable of supporting varied procurement scenarios.
- Stanford Advanced Materials (SAM) leverages manufacturing experience to supply high-quality silicon monoxide for electronic and industrial uses. Its long-standing production background supports a reliability narrative that resonates with buyers seeking stable supply and predictable specifications.
- Unilong Industry Co., Ltd. focuses on pieces and powder for coating and material applications, targeting customers that need practical forms for surface engineering and coating workflows.
- Hebei Yanxi Chemical Co., Ltd. and Hefei TNJ Chemical Industry Co., Ltd. operate within the inorganic chemical space, supplying silicon monoxide as part of broader chemical portfolios. Their presence highlights how the material is integrated into wider chemical supply chains, where procurement efficiency and portfolio breadth can be as important as isolated product specs.
The strategic positioning of these players reveals several differentiation levers. Some compete on purity and application alignment, others on product form and process support, and still others on portfolio breadth and regional availability. What is notable is that none of these approaches is inherently superior; rather, their effectiveness depends on the customer’s technical requirements, procurement model, and risk tolerance.
Market evolution is likely to follow a path of partial consolidation alongside continued specialization. On one hand, buyers increasingly prefer suppliers that can demonstrate consistent quality, regulatory familiarity, and application expertise, which may favor larger or more integrated players over time. On the other hand, the diversity of end uses—from packaging barriers to battery development to vacuum deposition—creates room for specialized manufacturers that can serve narrow but high-value segments. New entrants may find opportunities by focusing on underserved application niches, offering custom particle or form factors, or building stronger technical service capabilities around deposition and coating processes.
For competitive strategy, the key question is not simply who has the largest footprint, but who can reduce uncertainty for the buyer. Suppliers that combine reliable purity, clear trade documentation support, and application-relevant product forms are better positioned to command preference in procurement decisions, especially as customers move from spot buying toward longer-term supply relationships.
Future Trends Forecast
Looking ahead three to five years, several trends are likely to shape the market’s direction and create actionable opportunities.
Carbon Monoxide Market
1. Higher-purity, application-tailored forms will become the norm in premium segments. As silicon monoxide is integrated into more performance-sensitive workflows, buyers will increasingly differentiate between commodity-grade supply and specification-driven material. This will reward suppliers that invest in controlled reaction conditions, consistent particle morphology, and transparent quality documentation. The commercial opportunity lies in shifting from price-based competition to value-based positioning, where reliability and specification alignment justify premium margins.
2. Battery-related and energy storage workflows will continue to be a strategic growth vector. The broader interest in silicon-based anode development and energy density improvements is not a short-lived trend; it reflects a structural interest in next-generation storage materials. Silicon monoxide’s role in these workflows may evolve as formulations and processing methods mature, but the directional signal is clear: materials that support battery performance and manufacturing consistency will remain in focus. Companies that build application expertise and supply readiness for this vector can capture a growing share of demand, provided they can navigate technical qualification cycles and scale requirements.
3. Trade transparency and regional sourcing strategies will intensify. With active export flows across multiple shippers and destination markets, procurement teams are likely to place greater emphasis on supply visibility, documentation reliability, and regional resilience. This trend creates opportunities for suppliers that can offer predictable lead times, clear compliance support, and flexible sourcing arrangements. At the same time, it introduces risk for companies that rely on opaque supply chains or assume that duty-free classification automatically translates into frictionless trade. Regulatory interpretation, documentation quality, and destination-specific requirements will continue to matter.
PW Consulting
These trends carry inherent uncertainties. Technological adoption in battery anodes may proceed at different speeds across vehicle platforms and cell manufacturers. Energy costs and feedstock availability could affect production economics, particularly for energy-intensive synthesis routes. Trade documentation and compliance expectations may become more stringent in certain jurisdictions, adding cost and administration even where tariffs remain favorable. Decision makers should therefore treat growth opportunities as conditional on operational readiness, not as automatic outcomes of market expansion.
Actionable Guidance for Decision Makers
The market’s direction offers different implications depending on a company’s role in the value chain. The following recommendations are designed to translate market dynamics into practical next steps.
For Manufacturers and Material Suppliers
Focus on specifying and communicating purity, form consistency, and application fit rather than competing solely on unit price. Customers in deposition, coating, and battery-related workflows are increasingly weighing total process performance, so suppliers that provide clear technical documentation, reproducible product forms, and responsive support can differentiate more effectively. At the same time, review production economics with energy efficiency and feedstock reliability in mind, since these factors will influence margin stability as demand scales.
For Investors and Strategic Planners
Evaluate exposure to silicon monoxide not as a single market bet but as a cross-cutting enabler across electronics, energy storage, and industrial coatings. The most resilient opportunities are likely to be tied to suppliers or downstream users that can demonstrate application-specific value, reliable compliance handling, and the ability to serve multiple verticals without diluting quality. When assessing potential investments or partnerships, pay attention to qualification readiness, supply chain transparency, and the company’s ability to navigate trade documentation and regional sourcing requirements.
Silicon 28 Market
For Procurement and Sourcing Leaders
Strengthen technical qualification processes before committing to volume supply. Given the variability in product forms and purity ranges across the supply base, spot purchasing without specification alignment can create downstream variability and hidden costs. Build a shortlist based on documented purity consistency, form suitability for the intended process, and trade compliance reliability. Where possible, favor suppliers that can support predictable documentation and lead times, as these attributes reduce operational friction in multi-source or multi-region procurement strategies.
For organizations that need deeper segmentation, region-specific trade dynamics, and customized scenario planning, a more detailed research view can help translate these strategic signals into precise procurement, investment, and production decisions. A comprehensive report is available for teams that require granular data, application-level breakdowns, and tailored recommendations aligned with specific operational objectives.
For detailed analysis of this topic, please visit the official page: Silicon Monoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Building Safer Workplaces Through Smarter Employee Training
In demanding work environments, employee training needs to be treated as much more than an annual obligation or a compliance exercise. Workers routinely handle sophisticated equipment, complex systems, and procedures that can change with little warning. Under these conditions, even a small mistake can produce serious consequences. Training should therefore remain an active part of the overall safety strategy one that responds to workplace hazards, strengthens judgment, and helps stop incidents before they occur.
Organizations can achieve stronger results when learning is treated as an operational protection rather than simply a regulatory duty. A useful training framework is continuous, measurable, and accountable. Digital learning platforms can support this model by providing instruction based on job responsibilities, checking competency during normal operations, and keeping reliable records of training, certifications, and authorization for specific tasks. Bringing courses, assessments, and certification tracking together also promotes consistency when procedures are revised, requirements change, or employees and contractors enter or leave a workplace.
Training That Improves Everyday Work
When learning is woven into daily operations, it can influence safety and performance instead of merely transferring information. Rather than asking employees to sit through long sessions well before they need the knowledge, modern approaches can provide useful guidance closer to the moment it matters.
Microlearning is especially useful in this approach. Brief, focused modules allow workers to reach essential information connected to their responsibilities from any device. Training becomes easier to access and more closely connected with operational needs, while interruptions to productive work can be minimized.
Learning also becomes more effective when it reflects the responsibilities of roles. Operators, supervisors, maintenance teams, and contractors encounter different hazards, pressures, and expectations, so identical generic material may not address their needs. Activities involving confined spaces, lockout procedures, or hot work require instruction that reflects the conditions workers may encounter. Company policies, compliance obligations, and client expectations can be built into learning as well, reducing reliance on scattered paperwork or inconsistent explanations from people.
Digital learning can also provide clearer evidence of competency instead of treating course completion as proof of capability. Records of training, assessment results, and certifications can be organized in one place, creating useful evidence of workforce readiness. Such information can support inspections and audits while helping organizations verify that expected requirements are being applied consistently.
Keeping Learning Current as Conditions Change
Industrial workplaces are constantly evolving. Equipment may be replaced, procedures can be updated, and workforce needs may shift. Large projects can face additional complexity when contractors regularly rotate, making it harder to keep skills and qualifications current. Traditional classroom programs may be less flexible in these circumstances because updating materials requires coordination, while revised information may not reach every worker or site in the same way.
A digitally managed learning environment can address many of these challenges. When new hazards or competency gaps are identified, revised instruction can be shared more rapidly. Learning can therefore stay current, accurate, and connected to operating conditions. Organizations can establish common expectations across several facilities while still adapting content for regional requirements, language preferences, and project specific circumstances. Training records can also give managers a clearer picture of certification status, completed courses, expiration dates, and workforce learning history.
Built Around Real Operational Needs
Training is most useful when it fits naturally into daily work rather than creating an unnecessary interruption. Effective learning systems consider shift patterns, established routines, and the responsibilities attached to positions. Defined learning paths make expectations easier to understand, while reminders and refresher activities help employees maintain knowledge and competency.
Certification tracking becomes more manageable when it is connected with learning. Upcoming qualification expirations can be monitored automatically, while advance notifications can reduce the risk of unexpected gaps. Contractors can also complete required onboarding before reaching a site, helping them begin work with an understanding of safety expectations, workplace rules, and required procedures.
Centralized oversight allows organizations to maintain consistent practices across locations while preserving local variations. Audit preparation can become more efficient when dashboards provide a view of participation, assessment outcomes, and completion records. In some workplaces, training can even function as an operational control, with access to certain activities limited until required learning has been successfully completed.
Turning Learning Into Operational Value
Training can provide practical benefits when it becomes part of operational management. Employees are better prepared for permit driven activities when required instruction and competency checks have already been completed. Safety awareness initiatives can also be introduced quickly when new concerns appear, allowing organizations to address risks before they develop into incidents.
Project mobilization and site startup can be more orderly when employees and contractors arrive with a common understanding of requirements and expectations. Contractor oversight is strengthened through consistent learning standards and competency checks. Certification renewals can be planned ahead of time rather than becoming urgent tasks at the last minute. When workers receive timely instruction that reflects the conditions they encounter, organizations can also create conditions that support fewer incidents over time.
Putting the Learning Framework Into Action
Implementation should begin by linking job responsibilities with workplace hazards and permit requirements. That connection provides the basis for a structured learning strategy. Organizations can then develop focused learning paths that bring together essential knowledge, role specific instruction, and scheduled refresher activities.
Learning should become part of operational routines as well, including safety inspections and checks completed before work starts. Regular review of performance indicators and incident patterns can reveal where training needs reinforcement and where emerging risks require new or revised content.
When workforce competency is visible, current, and consistently verified, training can deliver benefits well beyond regulatory compliance. Organizations can create safer workplaces, strengthen day to day performance, and support productivity while offering greater protection to the people carrying out the work.
Book a free demo @ https://toolkitx.com/campaign/elearning/
Browse More
https://toolkitx.com/blogsdetails.aspx?title=Why-manual-excel-sheets-are-silently-draining-your-tank-farm%27s-profitability
WiFi Modules Market: Why 9.2% CAGR and Asia Pacific's 186.9M Lead Redefine Growth Beyond 2032
By PW Consulting, 2026-09-21
Navigating the WiFi Modules Market: Strategic Trends and Commercial Opportunities Through 2032
The WiFi modules market has evolved from a component-level consideration into a strategic enabler of connectivity across consumer, industrial, and infrastructure applications. Measured in USD across a forecast horizon extending to 2032, the market has demonstrated consistent expansion, with 2025 establishing a baseline around the mid-hundreds of millions and projected revenue climbing steadily toward the high hundreds by the end of the decade. This trajectory reflects more than incremental device proliferation; it signals a structural shift in how products are architected, certified, and deployed. For executives and investors evaluating connectivity roadmaps, the question is no longer whether WiFi modules matter, but how to align product portfolios, supply chains, and partnership strategies with a market that is maturing in capability while fragmenting in application requirements.
The growth profile over the analysis window points to a compound annual rate in the low-to-mid single digits, with revenue curves that accelerate as newer standards penetrate volume markets and legacy designs are refreshed. This pattern suggests a market that is not simply adding units, but progressively shifting toward higher-value configurations that bundle security, software stacks, and pre-certification support. At the same time, the competitive field remains moderately consolidated at the top tier, while the broader supplier base continues to expand through specialized players and regional champions. The result is a landscape where scale, certification readiness, and application-specific engineering increasingly determine who captures durable share.
Current Market Dynamics and Core Challenges
The current phase of the WiFi modules market is defined by three intersecting pressures that are reshaping sourcing decisions and product roadmaps. First, regulatory and trade dynamics are injecting cost and availability uncertainty into the component supply base. Tariff measures targeting advanced semiconductors and critical minerals have raised input costs and complicated procurement planning, while export controls on advanced semiconductors and high-bandwidth memory have extended to additional entities, altering the availability of certain chipset categories. These moves are not abstract policy signals; they directly affect lead times, bill-of-materials stability, and the feasibility of multi-source strategies for designs that depend on specific silicon families.
Second, the raw material and components environment has become more volatile at a time when demand for compute-intensive workloads is pulling memory and analog content in competing directions. Component pricing has experienced upward pressure in recent cycles, with lead times for analog ICs and microcontrollers lengthening meaningfully and memory products reaching multi-year highs. For module designers, this translates into tighter margin control, more frequent redesign risk, and a stronger incentive to lock in qualified alternatives before design freezes.
Third, critical mineral controls are reshaping the upstream economics of semiconductor fabrication used in connectivity products. Licensing requirements on gallium and germanium have introduced new constraints on materials that feed into chip production, reinforcing the importance of supplier diversification and regional sourcing strategies. These pressures are not uniform across all applications, but they raise the strategic cost of single-source dependency and reward companies that build redundancy into their qualification pipelines.
Key Growth Drivers Reshaping the Market
Underlying these challenges, several forces are propelling sustained expansion and redirecting value toward higher-performance, lower-power, and more application-tailored solutions.
Technology innovation and standards evolution. The migration toward newer WiFi generations is reshaping module design around throughput, latency, power efficiency, and coexistence with Bluetooth and other radios. Module suppliers are increasingly bundling SoCs, antennas, and firmware to deliver pre-certified platforms that reduce time-to-market for OEMs. Recent product announcements illustrate this direction: new module series built on advanced IoT SoCs target lower-power applications, while WiFi 7-oriented modules are being positioned for AI-capable PCs, embedded systems, and automotive/industrial environments. At the same time, long-range and low-power variants continue to broaden the addressable set of deployments, especially where battery life and range outweigh peak throughput as primary selection criteria.
PW Consulting Information & Electronics Research Center
Regulatory and certification dynamics. Certification remains a decisive gate for commercial adoption, particularly in regulated verticals and consumer markets where interoperability and security expectations are high. Securing alliance certification for specific module families has become a meaningful commercial milestone because it reduces OEM integration risk and accelerates launch cycles. The strategic implication is that module suppliers that can reliably deliver certified, documented, and supported platforms gain a structural advantage over component-only offerings, especially for customers that lack in-house RF compliance resources.
Demand-side shifts in industrial, smart, and edge applications. Demand is being pulled by expanding deployments in smart environments, industrial automation, and edge-connected devices, where WiFi is increasingly paired with local processing and sensor integration. Consumer electronics continue to anchor volume, but the growth narrative increasingly includes use cases that require robustness, longer lifecycle support, and environmental resilience. This shift is changing procurement priorities: buyers are weighing not only unit price but also temperature ranges, firmware update pathways, lifecycle availability, and the supplier's ability to support certification updates over product lifespans.
Supplychain and cost structure reconfiguration. Cost structures are being re-evaluated in light of component lead-time variability and the increasing value of integration. Modules that consolidate radios, processing, and support services can reduce total integration effort and de-risk compliance, which is especially attractive when internal engineering bandwidth is constrained. For suppliers, the cost equation now favors designs that balance performance with material availability and that offer predictable lifecycle planning, since customers are less willing to accept abrupt obsolescence or unmanaged pin-to-pin replacements.
Competitive Landscape and Leading Strategies
The competitive field combines well-established semiconductor and module specialists with regional players that compete on integration ease, certification readiness, and vertical-specific support. Several patterns define the current landscape and point to where differentiation is being earned.
Embedded Wi Fi Modules Market
Differentiation through pre-certified platforms and ecosystem alignment. Companies that focus on pre-certified WiFi and Bluetooth modules are building advantage by shortening integration cycles and lowering compliance risk for customers. Recent certification milestones and new module series based on leading IoT SoCs demonstrate a strategy centered on pairing proven silicon with turnkey module design, firmware, and documentation. Participation in major industry events further signals a push toward edge AI and IoT use cases, where the value proposition extends beyond connectivity to include ease of integration and application support.
Verticalization and industrial-grade positioning. A parallel strategy emphasizes ruggedized, industrial-grade modules and combo offerings that address harsher environments, longer support horizons, and specialized regulatory requirements. Suppliers in this tier are expanding portfolios to cover WiFi, long-range variants, and cellular-WiFi combos, broadening the set of deployments they can serve. The commercial logic is clear: industrial, medical, and infrastructure customers often prioritize availability, support, and environmental specs over absolute lowest unit cost, which creates room for premium positioning when product reliability is demonstrable.
Silicon-and-module coupling and reference designs. SoC providers that supply reference modules and partner ecosystems are reinforcing their position by enabling faster certification and more predictable performance. This model benefits customers that want consistent behavior across batches and suppliers that can scale volume without reinventing integration for each design. Where SoC vendors and module builders align closely, the market sees faster proliferation of certified designs and tighter control over RF performance and software quality.
Consolidation pressure and new-entry opportunities. The market exhibits moderate concentration at the top, which suggests that scale, portfolio breadth, and certification pipelines increasingly matter. At the same time, fragmentation persists in niche segments, creating openings for specialists that can deliver targeted solutions with strong documentation and lifecycle support. New entrants and regional champions can compete not by matching the broadest portfolios, but by solving specific integration, compliance, or environmental challenges better than generalist suppliers. Over time, the likely evolution is a mix of consolidation among scale players and continued specialization among application-focused vendors, with partnership and acquisition activity linking silicon, module, and vertical expertise.
Forward Outlook: Trends and Commercial Opportunities
Looking across the next three to five years, several trends are likely to shape where value accumulates and how participants should position themselves.
Shift toward integrated, certified platforms as the default procurement model. As integration complexity and compliance expectations rise, more buyers are expected to favor pre-certified modules and supported platforms over discrete component assemblies. This trend creates opportunities for suppliers that can offer reliable certification, clear documentation, and predictable lifecycle management, while increasing pressure on vendors that rely primarily on price competition without robust support. The commercial upside lies in becoming a trusted integration partner rather than a commodity source, especially in segments where time-to-market and regulatory risk dominate purchasing decisions.
WiFi Home Router Market
Performance-tier segmentation will deepen. The market is moving toward clearer segmentation between high-throughput, low-latency designs for AI-capable compute and premium consumer devices, and low-power, cost-sensitive designs for IoT and battery-operated deployments. This divergence rewards suppliers that can tailor architectures to distinct workloads and environments rather than offering one-size-fits-all products. Opportunity exists in bridging these tiers with modular architectures that allow customers to scale features while maintaining compatibility, and in providing clear migration paths as standards and silicon evolve.
Resilience and multi-source strategies will become procurement priorities. Ongoing trade measures, export controls, and component price volatility are likely to keep supply resilience on the agenda for enterprise and industrial buyers. Companies that can demonstrate qualified alternatives, transparent lead-time communication, and regional sourcing options will be better positioned to retain and expand accounts during periods of disruption. The associated risk is that over-reliance on a narrow set of silicon families or single-region suppliers may expose product lines to sudden redesign costs or launch delays, particularly if controls or material constraints tighten further.
Long-range and specialized connectivity will expand addressable deployments. As deployments extend into smarter infrastructure, industrial monitoring, and longer-range sensing, variants that balance range, power, and cost will find expanding use cases beyond traditional indoor networking. This creates room for suppliers that can pair appropriate radio characteristics with robust mechanical and environmental packaging, along with support for vertical-specific certification and lifecycle needs. The key uncertainty is how quickly standards, spectrum conditions, and ecosystem support converge to make these variants mainstream in volume applications.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to treat module selection as a platform decision rather than a component transaction. That means evaluating suppliers not only on unit economics, but also on certification status, documentation quality, firmware support, environmental specifications, and lifecycle commitments. Building qualified alternatives into designs early can reduce redesign risk if lead times or controls shift, and partnering with suppliers that provide pre-certified platforms can compress integration timelines while lowering compliance exposure. Where products target industrial, medical, or infrastructure markets, investing in ruggedized requirements and long-term availability planning is likely to pay dividends in customer trust and repeat business.
For investors, the attractive signals are found in suppliers that combine certification readiness with clear vertical focus and disciplined lifecycle management. Companies that can demonstrate recurring value through integration support, application-specific engineering, and reliable supply communication are better positioned to defend margins than those competing solely on price in commoditizing segments. At the same time, it is worth monitoring exposure to regulatory and material constraints, since concentrated dependency on specific silicon or materials can amplify downside if trade or licensing conditions evolve unfavorably. Portfolio breadth, ecosystem partnerships, and evidence of repeat design wins in demanding verticals are useful indicators of durable positioning.
For procurement and sourcing leaders, resilience should be built into the sourcing model through multi-source qualification, clear escalation paths for lead-time changes, and contractual clarity around lifecycle and obsolescence. Where possible, prioritize suppliers that provide transparent roadmaps, predictable certification updates, and documented alternatives for critical designs. Balancing performance requirements with supply reality is especially important in periods when memory, analog, and MCU availability are under pressure, since over-optimizing for a single optimal component can create hidden risk if conditions shift. In practice, the strongest sourcing strategies combine technical fit with redundancy, support quality, and a clear view of how trade and material dynamics may affect future revision cycles.
For organizations that need granular segmentation, customer-level demand signals, and tailored scenario planning across regions, applications, and module types, deeper market data can materially sharpen planning and reduce guesswork in portfolio and sourcing decisions. Detailed breakdowns of revenue by region, type, and application, along with company-level positioning and recent development tracking, provide the resolution needed to prioritize investments, qualify suppliers, and time product refreshes with greater confidence. For teams evaluating next-step connectivity strategies, a more detailed research report can serve as a practical reference for aligning product roadmaps, sourcing plans, and investment theses with where the market is heading through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: WiFi Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fire Pump Market to Hit $665M by 2032: Why 4.96% CAGR Signals a Strategic Shift
By PW Consulting, 2026-09-21
Global Fire Pump Market: Strategic Trends, Competitive Dynamics, and Commercial Opportunities Through 2032
The fire pump sector has evolved from a commoditized infrastructure component into a strategically differentiated business segment where reliability, regulatory compliance, and technical integration define market positioning. Over the historical review window from 2020 through 2025, global market revenue expanded from approximately 375 million USD to 482 million USD, reflecting a compound annual growth rate of 4.96 percent. Forward projections through 2032 indicate continued expansion toward roughly 665 million USD, driven by sustained capital formation in commercial real estate, industrial facilities, and offshore energy infrastructure. The trajectory is not uniform. Growth phases are shaped by regulatory cycles, regional construction activity, raw material volatility, and the pace at which manufacturers integrate monitoring capabilities, hydraulic efficiency, and application-specific engineering into product portfolios.
The market structure remains moderately concentrated. Three leading players collectively account for approximately 45 percent of total revenue, while the top five capture around 55 percent. This concentration level indicates a sector where established manufacturers hold meaningful share through product breadth, certification expertise, and long-term service relationships, yet it also leaves meaningful room for regional specialists, project-driven integrators, and technology-enabled entrants to capture niche positions. For executive teams evaluating exposure to fire protection equipment, the landscape presents a blend of stable baseline demand, cyclical project volatility, and clear differentiation opportunities for firms that can align product development with compliance evolution and end-user operational expectations.
Core Macro Dynamics and Structural Shifts
The revenue curve over the 2020 to 2025 period demonstrates steady expansion rather than explosive growth, which is typical of essential safety equipment markets where demand is anchored to building codes, industrial capacity additions, and asset life-cycle replacement programs. The moderation in growth velocity after the early post-2020 recovery reflects a normalization phase in which supply chains adjusted to elevated input costs, lead-time variability, and workforce constraints in fabrication and testing operations. As the market moves through the 2026 to 2032 forecast horizon, growth is expected to be sustained by ongoing urban development, industrial modernization, and energy sector projects that require integrated pump skids and high-pressure fire protection systems.
Three structural challenges define the current inflection point. First, raw material cost variability, particularly in steel-intensive pump housings, casings, and skid assemblies, introduces margin pressure and pricing complexity. Recent market data indicates that US steel prices averaged approximately 1,086 USD per metric ton in May 2026, up 3.5 percent from April, with hot-rolled coil near 1,109 USD per ton in June 2026. For manufacturers, this environment demands disciplined cost management, hedging strategies, and product engineering that reduces material intensity without compromising hydraulic performance or code compliance.
Second, regulatory frameworks continue to shape procurement cycles and product qualification requirements. The NFPA 20 Standard for the Installation of Stationary Pumps for Fire Protection remains the foundational reference for selection and installation as of 2026, while ASSE 15010 water-based fire protection certification qualifications and processes are undergoing changes beginning in early 2025 for inspection and testing of fire pumps. For suppliers and specifiers, evolving certification expectations create both administrative burden and competitive advantage for organizations that can streamline compliance, documentation, and field verification.
Third, the market faces an ongoing tension between standardization and customization. End-users in commercial building sectors increasingly favor packaged pump systems and compact configurations that simplify installation and maintenance, while oil and gas, marine, and large industrial facilities require engineered solutions that address site-specific pressure, flow, and environmental conditions. Balancing these demands requires manufacturing flexibility, modular design philosophies, and service teams capable of supporting both off-the-shelf and project-engineered deployments.
Key Drivers Shaping Market Trajectory
Technology Innovation and Monitoring Integration
A defining trend in the fire pump sector is the transition from purely mechanical reliability to connected, condition-aware systems. Historically, fire pumps were evaluated primarily on flow capability, pressure performance, and durability under intermittent duty cycles. Today, manufacturers are embedding telemetry, remote status monitoring, and diagnostic interfaces that enable facility operators and service contractors to track run-hours, alarm states, and performance deviations without manual inspection alone. This shift aligns with broader operational expectations in commercial real estate and industrial facilities, where uptime assurance, predictive maintenance, and rapid response capability are increasingly tied to asset management strategies.
Product launches in recent months illustrate this direction. In January 2026, Armstrong Fluid Technology introduced a new range of Constant Speed Vertical-In-Line Fire Pumps with high-pressure ratings up to 160 PSI for both 60Hz and 50Hz markets. The expansion into higher-pressure vertical in-line configurations reflects demand for compact, high-performance solutions suitable for taller buildings, space-constrained mechanical rooms, and applications where vertical footprint limitations constrain traditional horizontal installations. Vertical in-line designs also appeal to specifiers seeking reduced installation complexity and simplified alignment, provided the hydraulic and reliability requirements are met for the intended duty point.
Regulatory Environment and Certification Evolution
Regulation is not merely a constraint in this market; it is a design parameter and a commercial gate. NFPA 20 continues to define the baseline expectations for stationary fire pump selection and installation, creating a shared technical language across manufacturers, engineering firms, authorities having jurisdiction, and service providers. At the same time, evolving certification processes such as the ASSE 15010 updates introduce new scrutiny around inspection and testing practices. For manufacturers, the practical implication is that product approval, documentation rigor, and test protocol alignment are becoming differentiators in bidding and specification capture. Firms that invest early in certification readiness and clear compliance narratives tend to reduce deployment friction and improve win rates in regulated markets.
For purchasers and engineering teams, regulatory dynamism creates the need for supplier partners who can interpret standards consistently across regions and project types. In practice, this means that product capability alone is insufficient unless accompanied by repeatable installation guidance, commissioning support, and post-installation testing documentation that satisfies jurisdictional requirements. The regulatory layer therefore reinforces the value of established brands and technically credible service networks, while also opening opportunities for manufacturers that can simplify compliance through integrated documentation packages and standardized test evidence.
Demand-Side Changes in Commercial and Industrial Sectors
Demand patterns are shaped by the interplay of construction pipelines, facility modernization programs, and risk management priorities. Commercial buildings remain a dominant application area, with fire pump demand linked to new development, code-driven renovations, and replacement cycles in aging mechanical systems. Industrial facilities represent the second major demand pillar, where fire protection requirements intersect with process safety, hazardous area considerations, and large-scale infrastructure planning. In both segments, purchasers are increasingly focused on lifecycle economics rather than lowest initial equipment cost, which advantages solutions that combine reliability, serviceability, and remote monitoring capabilities.
Water Pumps Market
In parallel, energy sector activity continues to influence demand for engineered fire pump skids and high-pressure systems. Contract awards such as Sulzer’s November 2025 win for multiple integrated pump skids for Petrobras P-84 and P-85 FPSOs, with delivery in early 2026, underscore how offshore and large industrial projects generate specialized demand for integrated packages rather than standalone pump units. These projects reward suppliers with skid integration expertise, application engineering depth, and the ability to deliver systems that meet both fire protection and broader process interface requirements.
Supply Chain Resilience and Cost Structure Adaptation
The sector’s cost structure is sensitive to steel pricing, casting lead times, machining capacity, and the availability of qualified assembly and test labor. Companies that have strengthened supply chain resilience through multi-sourcing, forward inventory positioning, and modular subassembly strategies are better positioned to maintain delivery reliability during input price spikes. Equally important is product design discipline: pumps and skid systems that optimize material usage, standardize components across product lines, and reduce rework in fabrication can absorb input cost pressure more effectively than less standardized designs.
From a commercial standpoint, this environment favors manufacturers that can offer transparent pricing mechanisms, delivery certainty, and configuration flexibility. Procurement teams are increasingly weighing supplier reliability and compliance readiness against unit price, particularly for projects where delay costs and inspection risks are significant. This dynamic reinforces the strategic value of regional manufacturing footprints, localized service capabilities, and strong relationships with distributors and installation contractors.
Competitive Landscape and Strategic Positioning
Differentiation Vectors Among Leading Players
The market’s leading participants compete across several overlapping dimensions: product range breadth, application-specific engineering, certification depth, service networks, and increasingly, digital monitoring and integration. Pentair manufactures Aurora and Fairbanks Nijhuis fire pumps in horizontal and vertical configurations for global fire protection systems, positioning itself around established brand lines and a broad configuration portfolio. Grundfos produces fire pumps within a wider pump portfolio, leveraging its broader hydraulic competence and distribution relationships. NAFFCO offers fire protection pumps and related equipment for commercial and industrial use, often competing on regional responsiveness and bundled system solutions in Middle East and broader project markets.
Flowserve supplies industrial pumps including fire pump solutions, drawing on its broader engineered pump capabilities and industrial service infrastructure. Sulzer provides integrated fire pump skids and solutions for oil and gas and general fire protection, which aligns well with project-based demand where skid-level integration and application engineering matter. Kirloskar Brothers manufactures fire pumps for municipal and industrial applications, reflecting strength in regional manufacturing and cost-competitive engineering. SPP Pumps produces specialist fire pumps for fixed and portable systems, and Peerless Pump Company designs and manufactures horizontal and vertical fire pumps, including its FireConnect monitoring system, which illustrates how traditional pump manufacturers are extending into connected diagnostics to differentiate their offerings.
Armstrong Fluid Technology offers end-suction, horizontal, vertical in-line, and multi-stage fire pumps, giving it coverage across common commercial and industrial configurations. Rosenbauer produces fire pump systems integrated into fire trucks and apparatus, representing a distinct adjacency where pump capability is embedded into mobile fire suppression platforms. Waterous has manufactured US-made fire pumps, engines, and suppression equipment since 1886, competing on legacy, domestic production, and specialized suppression system integration. CET Fire Pumps MFG Inc. produces portable fire pumps with gas and diesel engines, plus skid units and foam systems, addressing niche mobile and specialized suppression needs. Xylem provides fire pumps under the AC brand for municipal and industrial fire protection, leveraging its broader water technology and infrastructure positioning.
Filter Pump Market
Market Concentration and Evolution Patterns
With a three-firm concentration near 45 percent and a five-firm concentration near 55 percent, the market is consolidated enough that scale, certification portfolios, and global distribution matter, yet fragmented enough that specialized players can win on application fit, regional proximity, and service agility. Over the next several years, two evolutionary patterns are likely to persist. The first is selective consolidation through capability acquisition, particularly where a manufacturer seeks broader product coverage, stronger skid integration capabilities, or access to a specialized monitoring or control technology. The second is continued differentiation among regional and application-focused players who compete on responsiveness, local certification expertise, and integration with local engineering and contractor ecosystems.
New entrants face meaningful barriers in this market, including code familiarity, test and certification requirements, service network expectations, and the need for reliable production quality. However, entry opportunities exist where modular packaged systems, compact vertical configurations, and connected monitoring reduce installation complexity and improve service economics. Companies that can demonstrate consistent compliance documentation, predictable lead times, and strong field support can gain traction even in competitive bidding environments.
Forward-Looking Trends and Commercial Implications
Trend One: Connected Diagnostics as a Standard Expectation
Remote monitoring and condition awareness are likely to move from premium option to expected capability in a growing share of commercial and industrial applications. As facility operators consolidate maintenance workflows and seek earlier warning of mechanical or electrical anomalies, pumps equipped with status telemetry, fault logging, and integration-friendly interfaces will be easier to specify and retain in service. The commercial implication is that manufacturers offering genuine monitoring value—rather than superficial connectivity—will improve after-service revenue potential and strengthen customer retention. A practical risk is that monitoring features must be supported by reliable data infrastructure, cybersecurity considerations, and service processes capable of acting on the information collected.
Trend Two: High-Pressure and Compact Vertical Solutions Gaining Share
The expansion of high-pressure vertical in-line options reflects demand for space-efficient, high-performance configurations suitable for tall buildings, constrained mechanical rooms, and applications where footprint and installation simplicity matter. This trend favors manufacturers that can deliver reliable vertical designs with robust sealing, alignment, and bearing arrangements while meeting code requirements across 50Hz and 60Hz regions. For procurement teams, compact and high-pressure solutions can reduce installation cost and improve building layout flexibility, but they require careful specification to ensure duty-point suitability and long-term serviceability.
Trend Three: Integrated Skid and Application-Engineered Packages in Energy and Industrial Projects
Offshore and large industrial projects continue to create demand for integrated skid systems that combine pumps, drivers, controls, and interface engineering into coordinated packages. Contract awards in FPSO and similar large-scale energy projects demonstrate that suppliers with skid integration capability and application-specific design competence can secure high-value projects even in concentrated markets. The commercial opportunity lies in expanding from component supply to system-level value creation, where integration reduces field engineering burden and improves commissioning reliability. A key uncertainty is project timing and capital expenditure variability in energy markets, which can shift demand from steady pipelines to episodic large contracts.
Strategic Implications for Decision-Makers
For Fire Pump Manufacturers and Integrators
- Align product roadmaps with compliance evolution and monitoring expectations. Invest in certification readiness, documentation clarity, and telemetry features that deliver actionable maintenance insight rather than simple data visibility.
- Strengthen cost and supply chain resilience. Standardize key components, manage steel exposure through procurement discipline and design efficiency, and protect delivery reliability during input price volatility.
- Expand toward system-level value where appropriate. Skid integration, packaged systems, and application-specific engineering can improve project margins and differentiate offerings in industrial, energy, and complex commercial deployments.
- Build service-aligned commercial models. In a market where uptime, installation correctness, and compliance documentation matter, service responsiveness and commissioning support can be as decisive as product specifications.
For Investors and Strategic Acquirers
- Prioritize businesses with durable compliance positioning, recurring service relationships, and credible monitoring or integration capabilities. Brand heritage alone is insufficient without modern product support and service economics.
- Evaluate regional specialists for capability tuck-ins. Strong local certification knowledge, contractor relationships, and application focus can complement broader platforms and accelerate entry into specific geographies or end markets.
- Monitor steel cost exposure and margin discipline as part of due diligence. Companies with standardized designs, flexible sourcing, and transparent cost pass-through mechanisms are better positioned to preserve profitability when input prices fluctuate.
- Watch for consolidation driven by product coverage gaps and digital capability needs. Targets that add vertical configurations, packaged systems, or connected diagnostics may offer strategic leverage beyond revenue scale.
For Procurement, Engineering, and Facility Decision-Makers
- Evaluate total lifecycle value rather than initial price alone. Installation complexity, commissioning support, compliance documentation, and serviceability can materially affect operating risk and long-term cost.
- Specify with monitoring and serviceability in mind. Where uptime assurance is critical, select configurations that enable condition tracking and simpler field support, and ensure that service providers can act on the data provided.
- Confirm compliance readiness early. Verify that proposed pump systems align with NFPA 20 expectations and current inspection and testing practices, including any changes to certification processes, to avoid delays during commissioning and jurisdictional review.
- Plan for supply-side variability. Given steel price movements and project timing risk, include delivery certainty, lead-time transparency, and contingency planning in procurement decisions, especially for time-sensitive commercial and industrial projects.
The fire pump market is entering a phase in which growth is supported by steady demand fundamentals, but competitive outcomes will increasingly depend on compliance mastery, product differentiation, and the ability to deliver reliable installation and service performance. The most compelling commercial opportunities will accrue to manufacturers and integrators that combine technical breadth with execution discipline, and to buyers who specify with lifecycle performance and regulatory alignment in mind. For teams that require detailed segmentation data, regional demand patterns, type-level revenue splits, and company-level competitive profiles to support planning and investment decisions, the full research report provides expanded datasets and tailored scenarios that build on the strategic direction outlined here.
PW Consulting
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com